Recording of Transactions - II
Class 11 Accountancy · Financial Accounting Part I · Chapter 4
163 members in the CBSE community
View all











CBSE Class 11 · AccountancyTrending
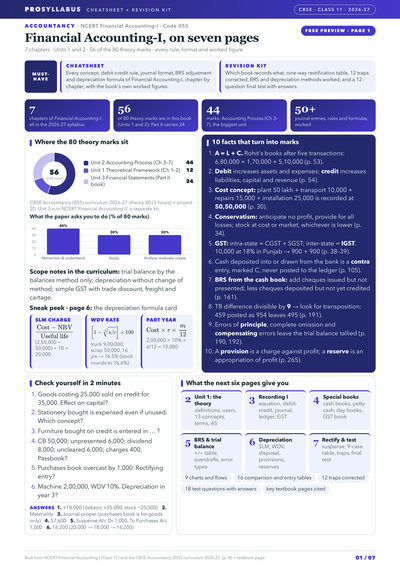
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
CBSE Class 11 · Accountancy
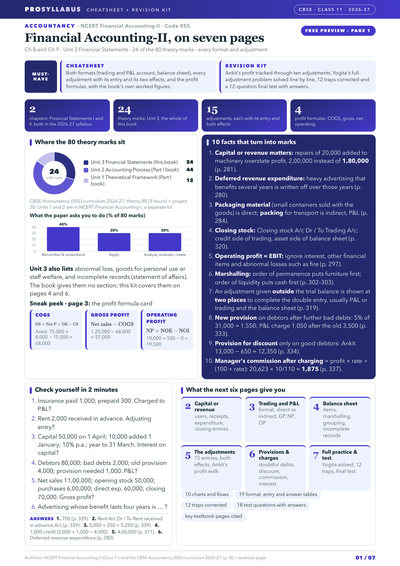
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
Summary
As a business grows, journalising every transaction becomes cumbersome, so the journal is sub-divided into special purpose books (also called subsidiary books or daybooks), each recording transactions of a similar nature. The main special purpose books are the cash book, purchases (journal) book, purchases return (return outwards) book, sales (journal) book, sales return (return inwards) book and the journal proper, which records transactions that fit none of the others. The cash book records all cash receipts and payments and serves as both a journal and a ledger account; it may be a single column cash book, a double (cash and bank) column cash book, or a petty cash book. In a double column cash book a contra entry records the transfer of money between cash and bank, appearing on both sides. The petty cash book records small day-to-day expenses, often maintained on the imprest system where the petty cashier is reimbursed for the amount spent. Purchases and sales books record only credit purchases and credit sales of goods, while the return books record goods returned. Entries from these books are posted to the ledger and the accounts are then balanced. The chapter also shows the recording of GST in subsidiary books and explains the balancing of accounts.