Financial Statements - II
Class 11 Accountancy · Financial Accounting Part II · Chapter 2
163 members in the CBSE community
View all










CBSE Class 11 · Accountancy
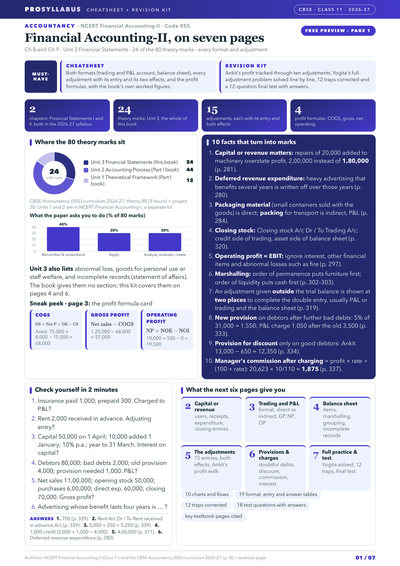
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
CBSE Class 11 · AccountancyTrending
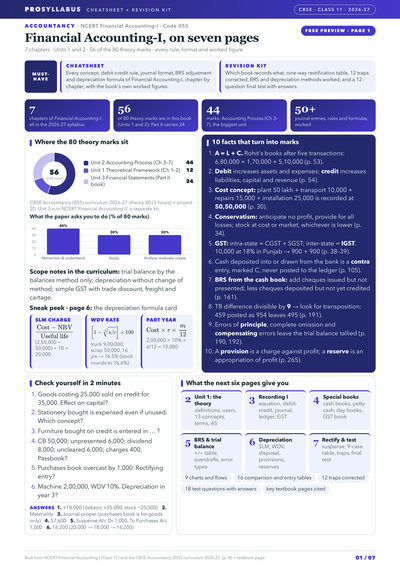
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
Summary
Simple final accounts assume no accounting complexities, but because income and financial position are determined on the accrual basis, several items need adjustment before final accounts give a true and fair view. The accrual concept requires that revenues be taken on an earned basis and expenses on an incurred basis, regardless of when cash is received or paid. The common adjustments discussed are: closing stock, which is valued and shown both in the trading account and the balance sheet; outstanding expenses, which are expenses incurred but not yet paid; prepaid (unexpired) expenses, which are paid in advance; accrued income, which is earned but not yet received; and income received in advance (unearned income), received but not yet earned. Further adjustments include depreciation on fixed assets, bad debts written off, provision for bad and doubtful debts created on debtors, provision for discount on debtors, and manager's commission on profits. Each adjustment generally affects two accounts—one in the trading or profit and loss account and the other in the balance sheet—so that the matching principle is satisfied. By incorporating all such adjustments, the trading and profit and loss account and the balance sheet present a true and fair picture of the profitability and financial position of the business.