Bank Reconciliation Statement
Class 11 Accountancy · Financial Accounting Part I · Chapter 5
163 members in the CBSE community
View all









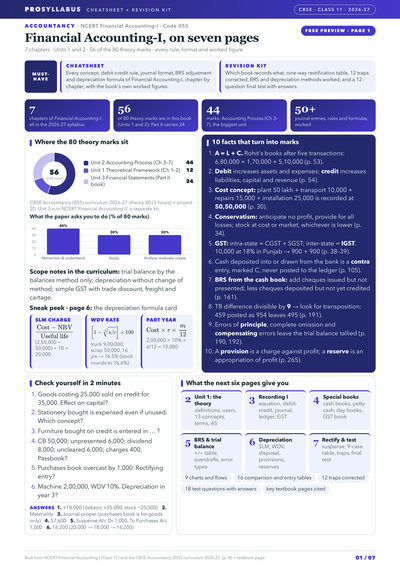
CBSE Class 11 · AccountancyTrending
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
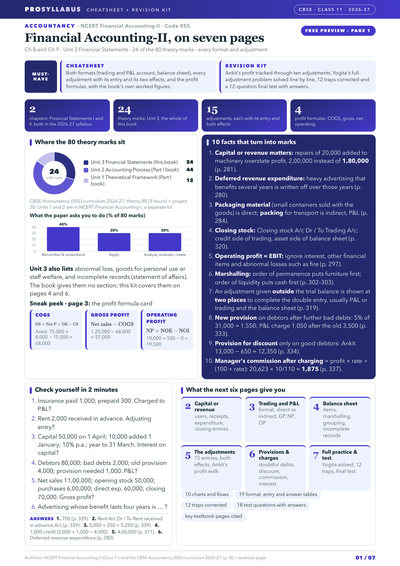
CBSE Class 11 · Accountancy
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
Summary
A bank reconciliation statement is prepared to reconcile the bank balance shown by the firm's cash book with the balance shown by the bank passbook or bank statement. The passbook is a copy of the customer's account as maintained by the bank, and in practice the two balances rarely tally on a given date. The differences arise mainly from timing differences in recording transactions and from errors. Timing differences include cheques issued but not yet presented for payment, cheques paid into the bank but not yet collected, direct debits made by the bank such as bank charges, amounts directly deposited by customers into the account, interest and dividends collected by the bank, direct payments made by the bank under standing instructions, and dishonour of cheques or bills. Errors may be committed either by the firm in its cash book or by the bank in the passbook. A favourable balance is a debit balance in the cash book (credit balance in the passbook), while an overdraft is a credit balance in the cash book (debit balance in the passbook). The statement can be prepared starting from either the cash book balance or the passbook balance, and may be drawn with or without first adjusting the cash book; in practice the cash book is usually adjusted before reconciliation.