Theory Base of Accounting
Class 11 Accountancy · Financial Accounting Part I · Chapter 2
163 members in the CBSE community
View all











CBSE Class 11 · AccountancyTrending
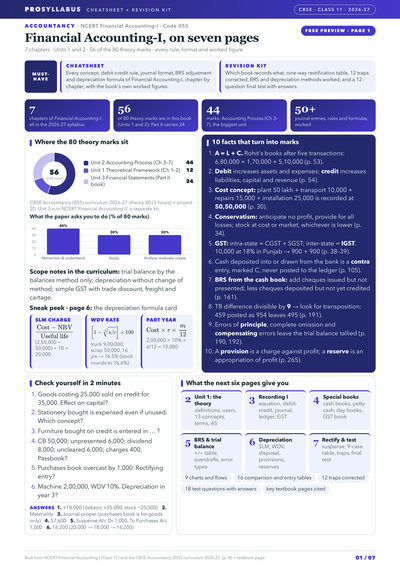
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
CBSE Class 11 · Accountancy
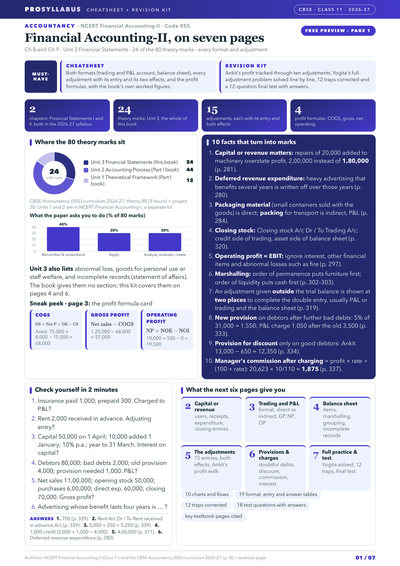
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
Summary
To make accounting information reliable and comparable, a sound theory base is required. The theory base consists of principles, concepts, rules and guidelines developed over time, together with the Accounting Standards issued by the Institute of Chartered Accountants of India (ICAI). Generally Accepted Accounting Principles (GAAP) are the rules adopted for recording and reporting transactions to bring uniformity in financial statements; the terms principles, concepts and conventions are used interchangeably as basic accounting concepts. The important concepts are business entity, money measurement, going concern, accounting period, cost, dual aspect, revenue recognition (realisation), matching, full disclosure, consistency, conservatism (prudence), materiality and objectivity. The dual aspect concept gives the fundamental accounting equation, Assets = Liabilities + Capital. Transactions may be recorded under the double entry system, which records both aspects of every transaction, or the single entry system, which is incomplete. From the timing of recognition, accounting may follow the cash basis (recording when cash is received or paid) or the accrual basis (recording when revenues and costs occur). Accounting Standards are written policy documents covering recognition, measurement, presentation and disclosure, issued to bring uniformity and comparability. The chapter also explains the Goods and Services Tax (GST), a destination-based tax with CGST, SGST and IGST components.