Trial Balance and Rectification of Errors
Class 11 Accountancy · Financial Accounting Part I · Chapter 6
163 members in the CBSE community
View all










CBSE Class 11 · AccountancyTrending
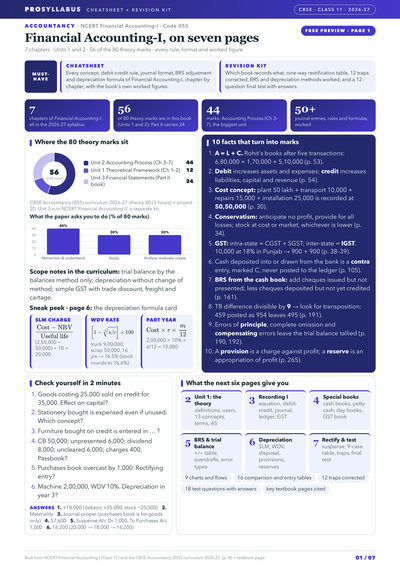
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
CBSE Class 11 · Accountancy
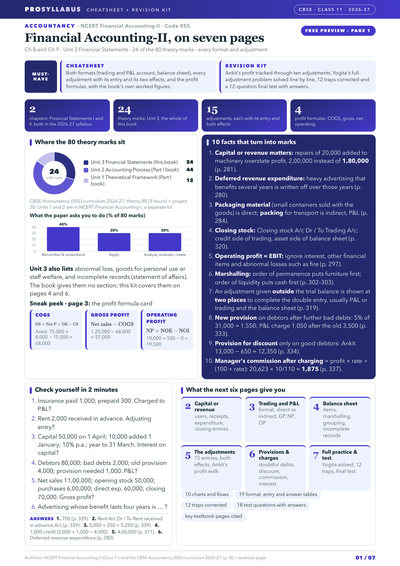
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
Summary
A trial balance is a statement showing the balances, or the totals of debits and credits, of all the ledger accounts on a particular date, prepared to verify the arithmetical accuracy of posting. Under the double entry system the total of debit balances should equal the total of credit balances. The objectives of preparing a trial balance are to ascertain the arithmetical accuracy of the ledger, to help locate errors and to assist in preparing the financial statements. It may be prepared by the totals method, the balances method, or the totals-cum-balances method, the balances method being most common. However, the agreement of a trial balance does not guarantee that the books are free from all errors. Errors are classified as errors of commission, errors of omission, errors of principle and compensating errors. Some errors affect the agreement of the trial balance (one-sided errors) while others do not (two-sided errors). When errors are detected, they are rectified: errors that do not affect the trial balance are corrected by passing a rectifying journal entry, while one-sided errors affecting the trial balance are corrected through a suspense account. A suspense account is opened temporarily to make the trial balance agree and is closed when all errors are located and rectified.