Recording of Transactions - I
Class 11 Accountancy · Financial Accounting Part I · Chapter 3
163 members in the CBSE community
View all











CBSE Class 11 · AccountancyTrending
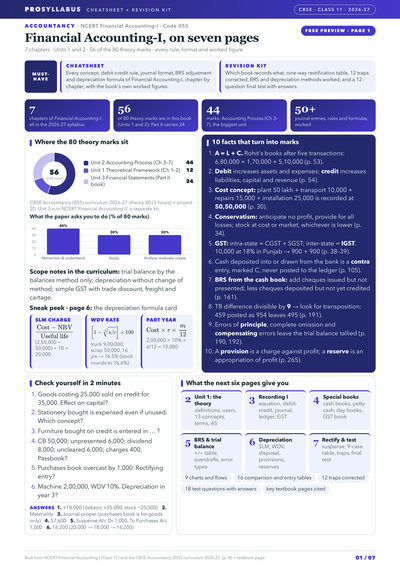
Financial Accounting-I: 56 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 44 marks: Unit 2, recording to depreciation
- Journal formats and special purpose books
- Traps from all seven chapters
- Bank reconciliation adjustments
- Depreciation formulas, book's worked figures
CBSE Class 11 · Accountancy
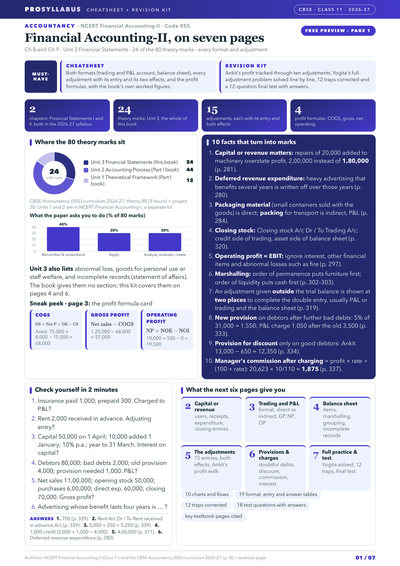
Financial statements: 24 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- Five calculations the paper keeps asking
- Each adjustment: one entry, two effects
- Both formats: trading and P&L, balance sheet
- Yogita illustration solved line by line
Summary
This chapter explains the first steps of the accounting process: identifying transactions, preparing source documents, applying the accounting equation, recording entries in the journal and posting them to the ledger. A business transaction is an exchange of economic consideration with a two-fold effect, evidenced by a source document or voucher such as a cash memo, invoice or receipt. Accounting vouchers may be cash, debit, credit or journal (complex) vouchers. Every transaction affects the accounting equation Assets = Liabilities + Capital, keeping both sides equal. The rules of debit and credit are applied: for assets and expenses, an increase is debited and a decrease is credited; for liabilities, capital and revenues, an increase is credited and a decrease is debited. The journal is the book of original entry where transactions are recorded chronologically with debit and credit accounts, amounts and a narration; this process is called journalising. The ledger is the principal book containing individual accounts, and transferring entries from the journal to the ledger is called posting. The chapter also illustrates the recording of transactions involving GST (CGST, SGST and IGST). The journal records data by transaction while the ledger classifies it by account, and ledger accounts are later balanced to find their net positions.