Controlling
Class 12 Business Studies · Business Studies Part I · Chapter 8
163 members in the CBSE community
View all










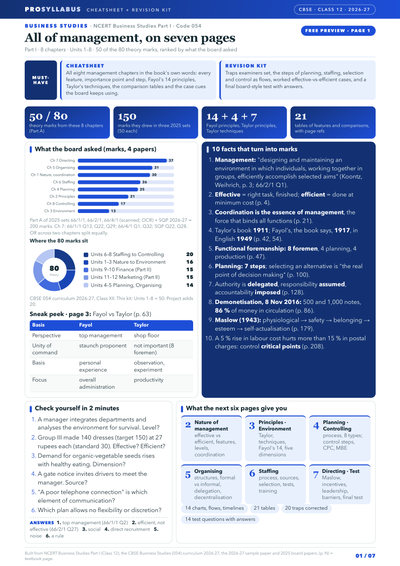
CBSE Class 12 · Business Studies
Directing: 37 marks in 4 papers, the most- Marks booster + cheatsheet: most-asked concepts in 2 lines each
- 8 chapters ranked by what the board asked
- 31 marks: Organising, a 6-marker every set
- 30 marks in 4 papers: nature of management
- 14 principles of Fayol
- Case cues the board keeps using
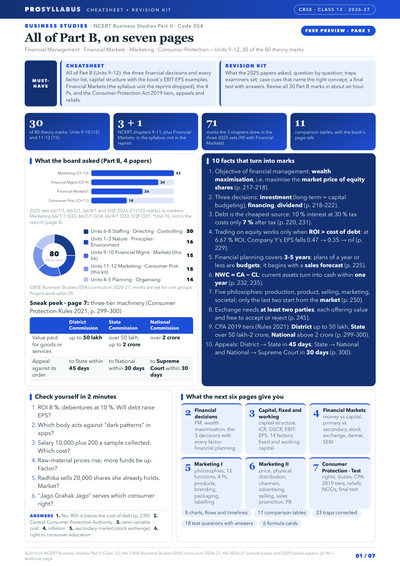
CBSE Class 12 · Business Studies
Financial Markets: 26 marks, not in NCERT- Marks booster + cheatsheet: key concepts in 2 lines each
- 15 marks each: Units 9–10 and 11–12
- 4 Ps of marketing, Unit 11
- Consumer Protection Act 2019 tiers, appeals
- Capital structure with EBIT-EPS examples
- The three financial decisions, every factor
Summary
Controlling means ensuring that the activities in an organisation are performed as per the plans, so that resources are used effectively and predetermined goals are achieved. It is a goal-oriented, pervasive function performed by managers at every level, and it brings the management cycle back to planning by analysing how far performance deviates from standards. The importance of controlling lies in accomplishing organisational goals, judging the accuracy of standards, making efficient use of resources, improving employee motivation, ensuring order and discipline and facilitating coordination in action. Controlling also has limitations: difficulty in setting quantitative standards, little control over external factors, resistance from employees and the fact that it can be a costly affair, especially for small firms. Planning and controlling are inseparable twins — planning provides the standards and controlling makes plans succeed; planning is prescriptive and looking ahead, while controlling is evaluative and looking back, yet both are forward and backward looking. The controlling process has five steps: setting performance standards, measurement of actual performance, comparing actual performance with standards, analysing deviations and taking corrective action. While analysing deviations, managers use critical point control (focusing on key result areas) and management by exception (attending only to significant deviations beyond the permissible limit) so that managerial time is well used. Techniques of control include traditional ones (personal observation, statistical reports, breakeven analysis, budgetary control) and modern ones (return on investment, ratio analysis, responsibility accounting, management audit, PERT and CPM, and management information systems).