Issue and Redemption of Debentures
Class 12 Accountancy · Accountancy Part II · Chapter 2
163 members in the CBSE community
View all










CBSE Class 12 · Accountancy
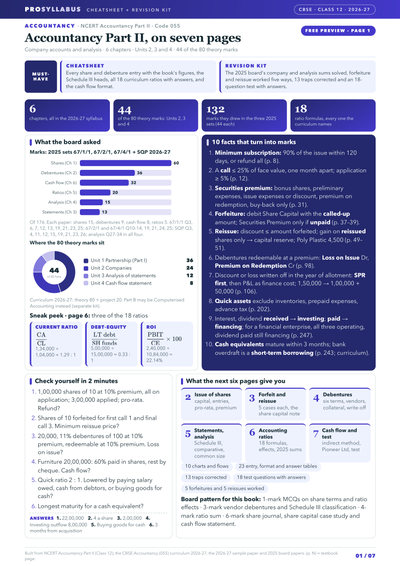
All 18 ratios, with the book's answers- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 15 marks in every 2025 set: share capital
- 9 marks in every 2025 set: debentures
- Common traps that cost marks, listed
- 6-mark cash flow in every paper
- 5 marks in every 2025 set: ratios
CBSE Class 12 · Accountancy
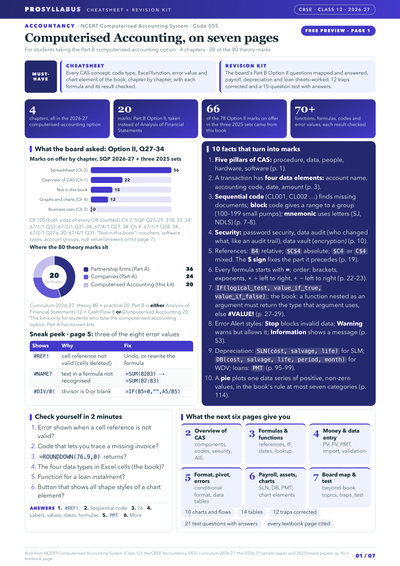
Spreadsheet: 56 of 105 Option II marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- 22 of 105 marks on offer: CAS overview
- Most asked item: error values
- What Q27–34 ask, answer by answer
- Every Excel function, result checked
CBSE Class 12 · Accountancy
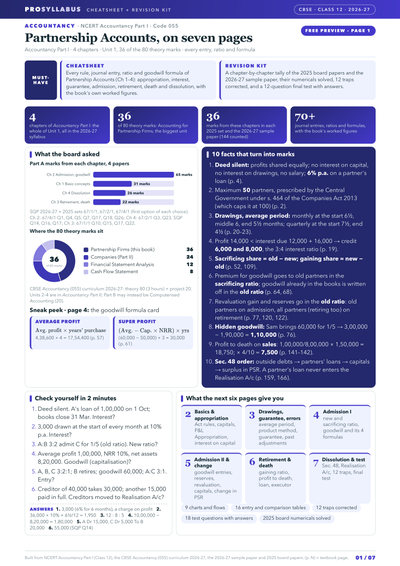
Partnership Accounts: 36 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- 65 board marks: Admission of a Partner
- 26 board marks: Dissolution
- 22 board marks: Retirement/Death
- Goodwill formulas with the book's figures
Summary
A debenture is a written instrument acknowledging a debt under the common seal of the company, containing a contract to repay the principal after a specified period and to pay interest at a fixed rate. The word comes from the Latin debere, meaning to borrow, and finance raised through debentures is long-term debt. Section 2(30) of the Companies Act 2013 says the term includes debenture stock, bonds and other securities, whether or not they create a charge on the company's assets. Debentures differ from shares: a debenture holder is a creditor, not an owner; interest is a charge against profit; and debentures are usually secured and redeemable. They may be classified on the basis of security, convertibility, permanence, negotiability and priority. Debentures can be issued at par, at a premium or at a discount, and for cash or for consideration other than cash; they may also be issued as collateral security for loans. The terms of redemption may differ from the terms of issue, giving rise to loss on issue of debentures. The chapter explains the accounting for the issue of debentures under various terms, the writing-off of discount or loss on issue, interest on debentures, and their redemption in a lump sum or by instalments out of the proceeds available.