Reconstitution of a Partnership Firm – Retirement/Death of a Partner
Class 12 Accountancy · Accountancy Part I · Chapter 3
163 members in the CBSE community
View all










CBSE Class 12 · Accountancy
Spreadsheet: 56 of 105 Option II marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- 22 of 105 marks on offer: CAS overview
- Most asked item: error values
- What Q27–34 ask, answer by answer
- Every Excel function, result checked
CBSE Class 12 · Accountancy
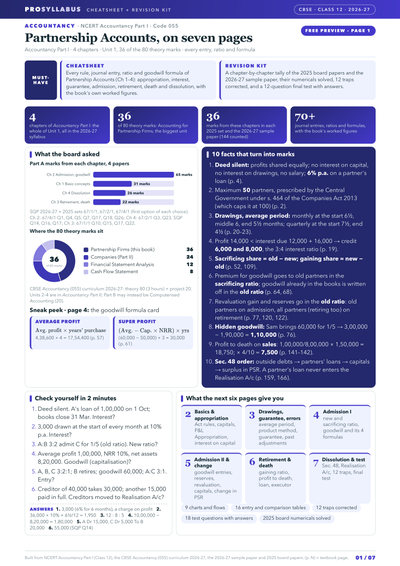
Partnership Accounts: 36 of 80 theory marks- Marks booster + cheatsheet: key concepts in 2 lines each
- 12 exam traps, listed
- 65 board marks: Admission of a Partner
- 26 board marks: Dissolution
- 22 board marks: Retirement/Death
- Goodwill formulas with the book's figures
CBSE Class 12 · Accountancy
All 18 ratios, with the book's answers- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 15 marks in every 2025 set: share capital
- 9 marks in every 2025 set: debentures
- Common traps that cost marks, listed
- 6-mark cash flow in every paper
- 5 marks in every 2025 set: ratios
Summary
The retirement or death of a partner also reconstitutes the firm: the existing partnership deed ends, and the remaining partners continue under new terms. The accounting treatment is broadly the same in both cases and centres on ascertaining the amount due to the retiring partner or to the legal representatives of a deceased partner. This sum includes the credit balance of the partner's capital and current accounts, the share of goodwill, the share of accumulated profits and reserves, the share in the gain on revaluation of assets and liabilities, the share of profit up to the date of retirement or death, and any interest on capital or salary due. From this, deductions such as drawings, interest on drawings, the share of any loss and the share of revaluation loss are made. The remaining partners gain a part of the profit share, so the new profit-sharing ratio and gaining ratio are calculated, and the retiring partner is compensated for goodwill through the gaining partners in their gaining ratio. Assets and liabilities are revalued and accumulated reserves distributed in the old ratio. The amount finally payable to a retiring partner may be paid in cash or transferred to a loan account, while the share due on death is transferred to the executor's account. The chapter ends with the preparation of the balance sheet of the reconstituted firm.