Determination of Income and Employment
Class 12 Economics · Introductory Macroeconomics · Chapter 4
163 members in the CBSE community
View all










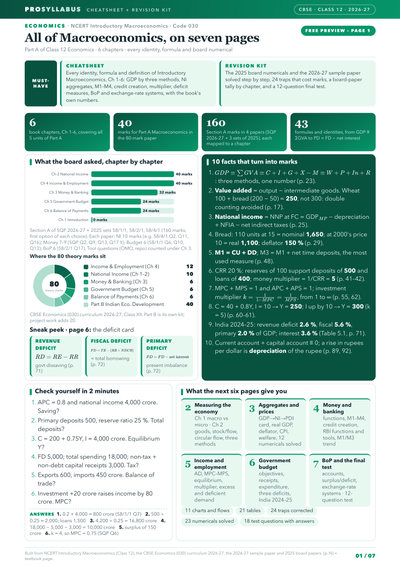
CBSE Class 12 · Economics
Macro marks by unit: Ch 4 leads with 12- Marks booster + cheatsheet: key concepts in 2 lines each
- 10 marks: National Income Accounting
- 3 methods for GDP, with identities
- M1–M4 and credit creation, Ch 3
- Every deficit measure of the budget, Ch 5
- 6 chapters: every formula, board numerical
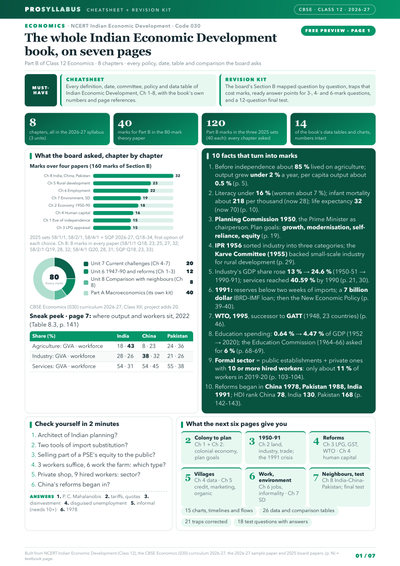
CBSE Class 12 · EconomicsTrending
Unit 7 (Ch 4–7) carries 20 marks- Marks booster + cheatsheet: key concepts in 2 lines each, common traps
- 12 marks: Unit 6, Ch 1–3
- 8 marks: Unit 8, India-China-Pakistan
- Every committee, policy and date, by chapter
- Data tables with the book's own numbers
- Common traps, corrected
Summary
This chapter develops the Keynesian theory of income determination, assuming a fixed price level and a given rate of interest so that output is determined by aggregate demand. Aggregate demand is the total planned (ex-ante) spending on final goods, made up of consumption, investment, government spending and net exports. Consumption depends on income through the consumption function \(C=\bar{C}+cY\), where \(\bar{C}\) is autonomous consumption and c is the marginal propensity to consume, \(\text{MPC}=c=\dfrac{\Delta C}{\Delta Y}\); the marginal propensity to save is \(\text{MPS}=1-c\). Investment is taken as autonomous. The economy is in equilibrium where planned output equals planned aggregate demand, that is where \(Y=AD\) (the 45-degree line meets the AD line), or equivalently where planned saving equals planned investment. A key result is the multiplier: an autonomous change in spending changes equilibrium income by a larger amount, since the investment multiplier is \(\dfrac{1}{1-c}=\dfrac{1}{\text{MPS}}\). The chapter also explains the paradox of thrift — when everyone tries to save more, total saving may not rise and income falls — and distinguishes full-employment equilibrium from situations of deficient demand (which causes unemployment and tends to lower prices) and excess demand (which tends to raise prices), introducing the idea of effective demand.