Reconstitution of a Partnership Firm – Admission of a Partner — Class 12 Accountancy
Accountancy Part I · Chapter 2
CBSE Class 12 community
View all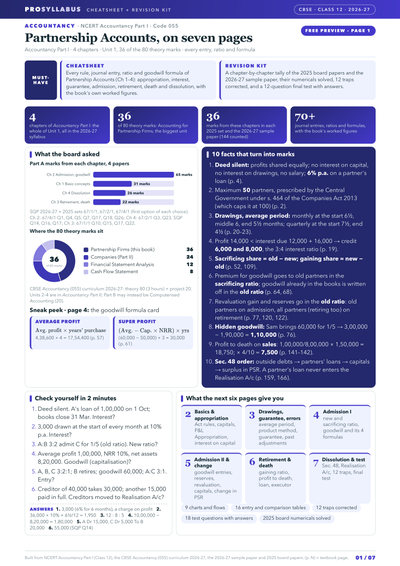
 9
- Accountancy
- Business Studies
- + 3 more
- Accountancy
 8
- Mathematics
- Physics
- + 3 more
- Physics
- Chemistry
- + 3 more
- Physics
 3
- History
 2
- हिंदी
 2
- Mathematics
 2
- Sociology
 2
- Economics
 2
- Home Science
 2
- اردو
- Urdu Elective
 3
- Geography
 2
- Flamingo
- Vistas
 2
- Political Science
 2
- Chemistry
 2
- Business Studies
 2
- हिंदी
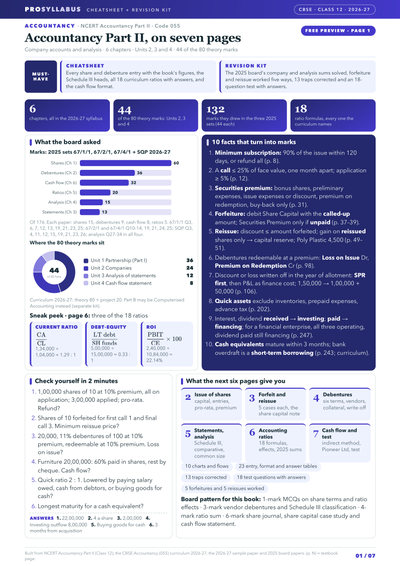
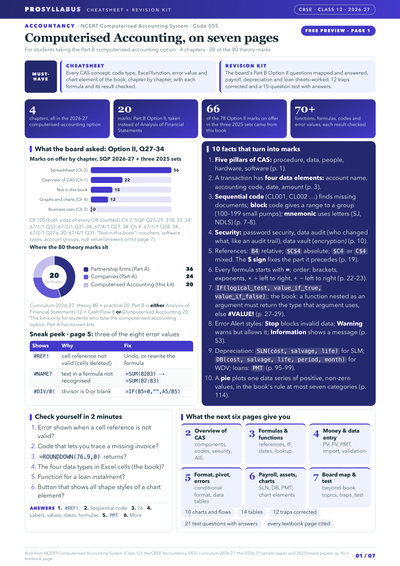
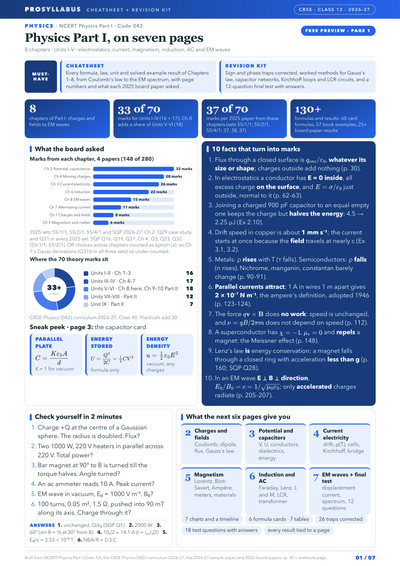
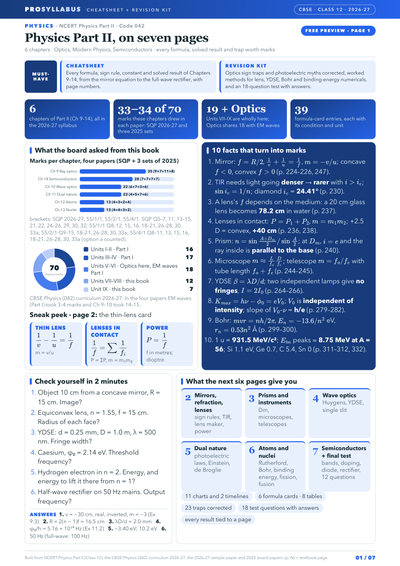
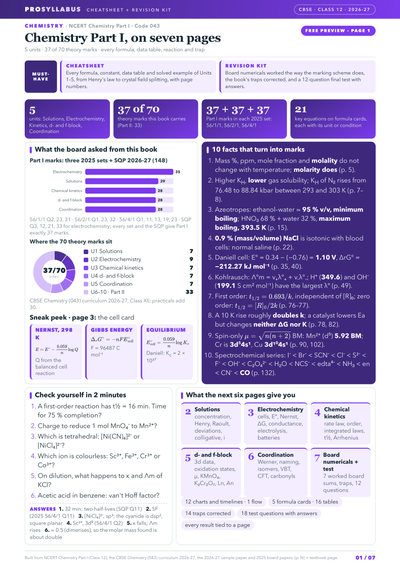
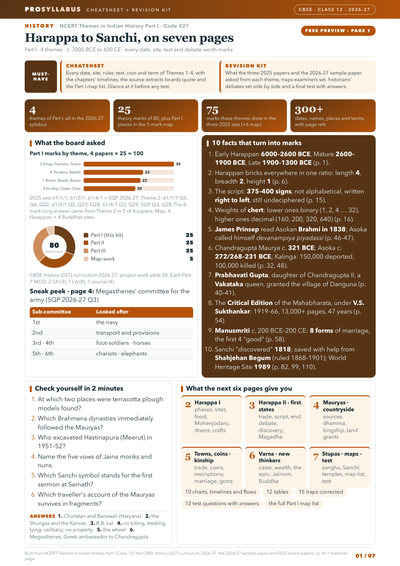
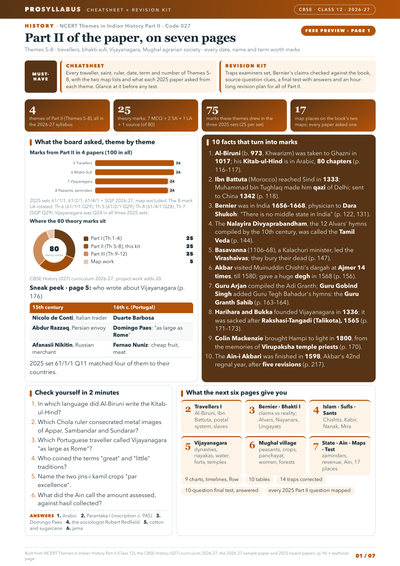
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
Chapter summary
Key ideas & terms
- Reconstitution
- A change in the existing agreement of partnership that ends the old partnership while the firm may continue.
- Sacrificing Ratio
- The ratio in which existing partners give up a part of their share of profit in favour of the new partner.
- Goodwill
- The value of a firm's reputation that enables it to earn higher than normal profits, valued by average profit, super profit or capitalisation methods.
- New Profit-sharing Ratio
- The ratio in which all partners, including the new one, share future profits after admission.
- Revaluation Account
- An account prepared to record the changes in the value of assets and liabilities at the time of reconstitution; its profit or loss belongs to the old partners.
- Premium for Goodwill
- The amount brought in by the incoming partner to compensate sacrificing partners for the share of profit they give up.
Extra questions & answers
What is meant by reconstitution of a partnership firm?
It is any change in the existing agreement of partnership, such as admission, retirement, death or a change in the profit-sharing ratio, which dissolves the old partnership.
What two main rights does a new partner acquire?
A right to share in the future profits of the firm and a right to share in the assets of the firm.
What is the sacrificing ratio and why is it computed?
It is the ratio in which the old partners surrender profit to the new partner; it is needed to credit them with the premium for goodwill.
Name the three methods of valuing goodwill.
Average profit method, super profit method and capitalisation method.
Why is a Revaluation Account prepared on admission?
To revalue assets and reassess liabilities so that any resulting profit or loss is shared by the old partners in their old ratio before the new partner joins.
How are accumulated reserves treated on admission?
Reserves and the credit balance of the Profit and Loss Account are distributed among the old partners in their old profit-sharing ratio.
How is the sacrificing ratio calculated?
Sacrificing ratio = old share minus new share for each old partner.
How is premium for goodwill brought in cash treated?
It is credited to the sacrificing partners in their sacrificing ratio, while cash or bank is debited.
What is super profit?
It is the excess of actual average profit over the normal profit expected on the capital employed.
When are partners' capitals adjusted after admission?
When the partners decide that their capitals should be in proportion to the new profit-sharing ratio, surplus or deficiency being adjusted through cash or current accounts.