Dissolution of Partnership Firm — Class 12 Accountancy
Accountancy Part I · Chapter 4
CBSE Class 12 community
View all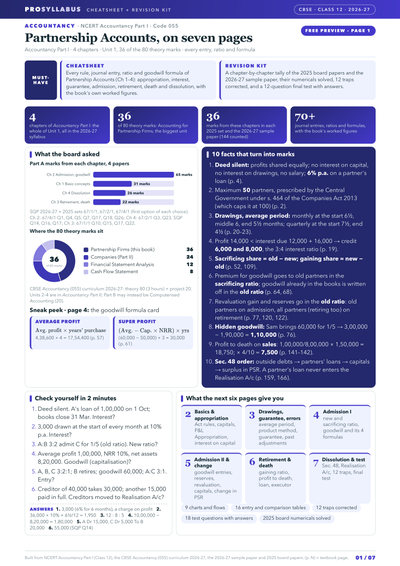
 9
- Accountancy
- Business Studies
- + 3 more
- Accountancy
 8
- Mathematics
- Physics
- + 3 more
- Physics
- Chemistry
- + 3 more
- Physics
 3
- History
 2
- हिंदी
 2
- Mathematics
 2
- Sociology
 2
- Economics
 2
- Home Science
 2
- اردو
- Urdu Elective
 3
- Geography
 2
- Flamingo
- Vistas
 2
- Political Science
 2
- Chemistry
 2
- Business Studies
 2
- हिंदी
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
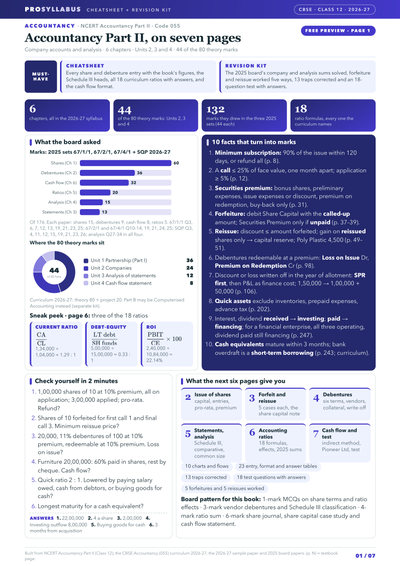
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
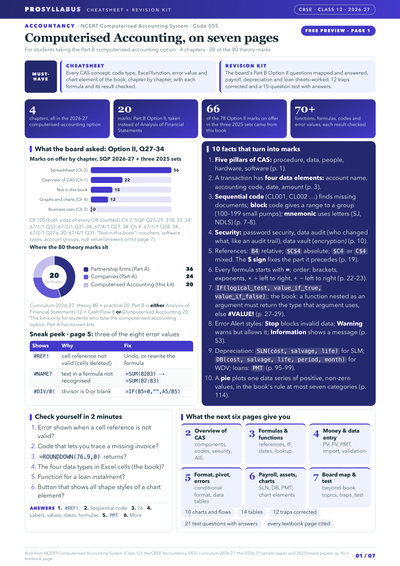
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
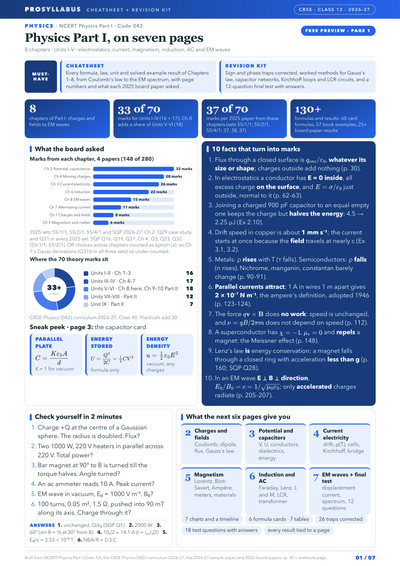
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
Chapter summary
Key ideas & terms
- Dissolution of Partnership
- A change in the relationship among partners while the firm continues its business as before.
- Dissolution of Firm
- The dissolution of partnership among all partners, bringing the firm's existence and business to an end (Section 39).
- Realisation Account
- The account prepared on dissolution to record the sale of assets, payment of liabilities and the resulting profit or loss.
- Realisation Expenses
- The expenses incurred in the process of winding up the firm, such as costs of selling assets and settling liabilities.
- Firm's Debts
- Liabilities owed by the firm to outsiders, which are paid out of the firm's assets before partners' claims are settled.
- Settlement of Accounts
- The order in which the firm's assets are applied—paying outside debts, partners' loans, and finally partners' capitals.
Extra questions & answers
Distinguish dissolution of partnership from dissolution of a firm.
Dissolution of partnership changes the partners' relationship while the firm continues; dissolution of the firm ends the firm's business and existence altogether.
Which section defines dissolution of the firm?
Section 39 of the Indian Partnership Act 1932 defines the dissolution of partnership among all the partners as the dissolution of the firm.
Name the modes of dissolution of a firm.
By agreement, compulsory dissolution, dissolution on the happening of certain contingencies, dissolution by notice and dissolution by the court.
What is the purpose of a Realisation Account?
To record the sale of assets and the settlement of liabilities so as to find the profit or loss on realisation.
Which items are not transferred to the Realisation Account?
Cash and bank balances, and fictitious assets or accumulated losses, are not transferred to the Realisation Account.
How is profit or loss on realisation distributed?
It is transferred to the partners' capital accounts in their profit-sharing ratio.
In what order are accounts settled on dissolution?
First outside liabilities, then partners' loans, and finally the partners' capital balances.
How are realisation expenses recorded?
They are debited to the Realisation Account; if borne by a partner, the partner's capital account is credited.
When can a court order dissolution of a firm?
On grounds such as a partner becoming of unsound mind, permanent incapacity, misconduct, persistent breach of agreement or the business running at a loss.
What happens to a partner's loan to the firm on dissolution?
It is repaid after outside liabilities but before the partners' capital accounts are settled.