Cash Flow Statement — Class 12 Accountancy
Accountancy Part II · Chapter 6
CBSE Class 12 community
View all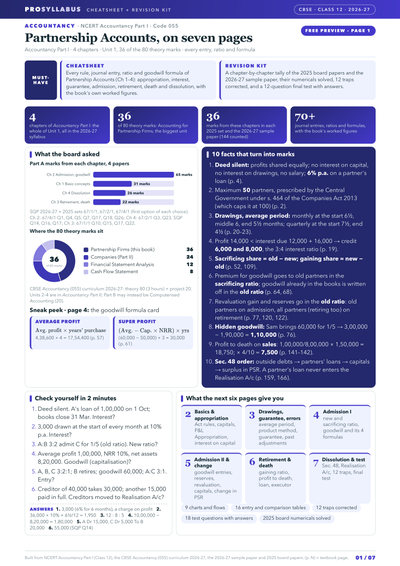
 9
- Accountancy
- Business Studies
- + 3 more
- Accountancy
 8
- Mathematics
- Physics
- + 3 more
- Physics
- Chemistry
- + 3 more
- Physics
 3
- History
 2
- हिंदी
 2
- Mathematics
 2
- Sociology
 2
- Economics
 2
- Home Science
 2
- اردو
- Urdu Elective
 3
- Geography
 2
- Flamingo
- Vistas
 2
- Political Science
 2
- Chemistry
 2
- Business Studies
 2
- हिंदी
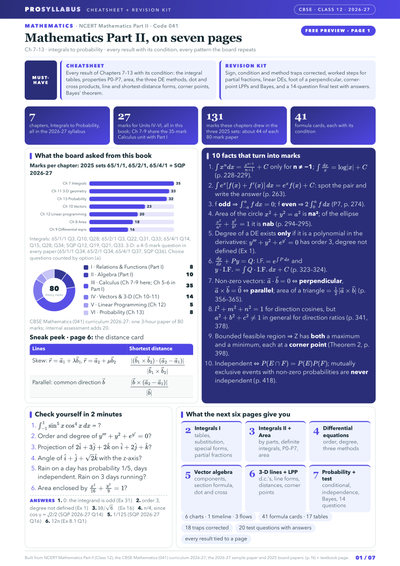
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
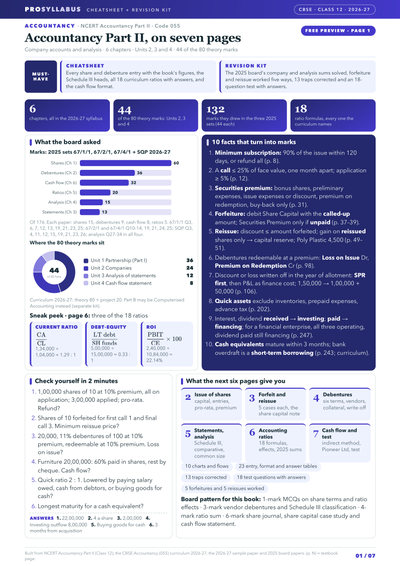
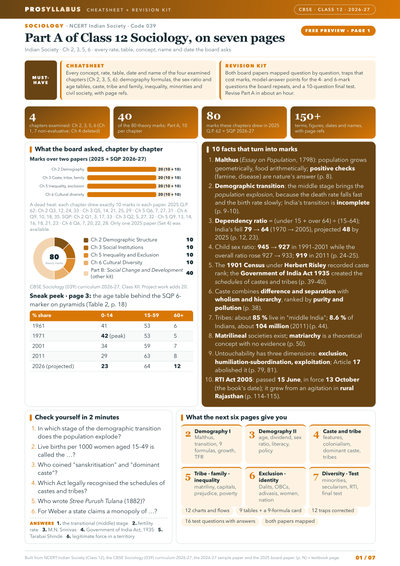
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
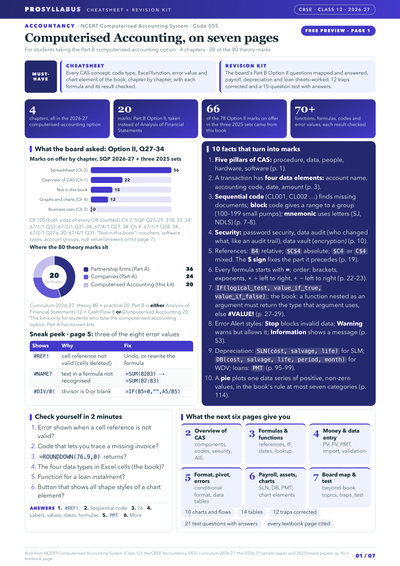
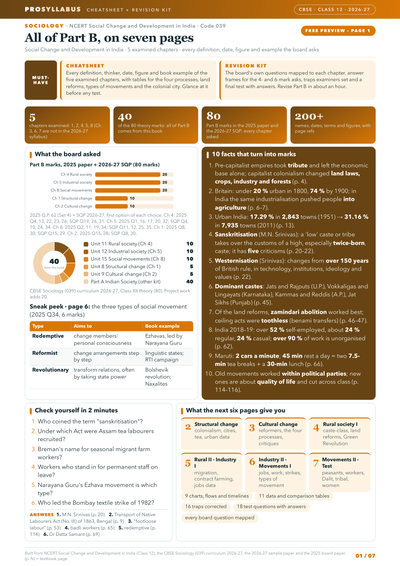
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
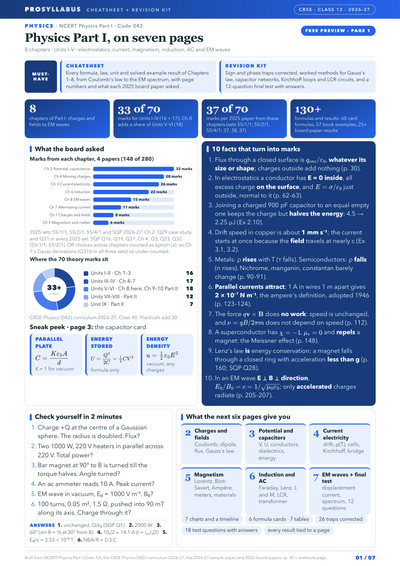
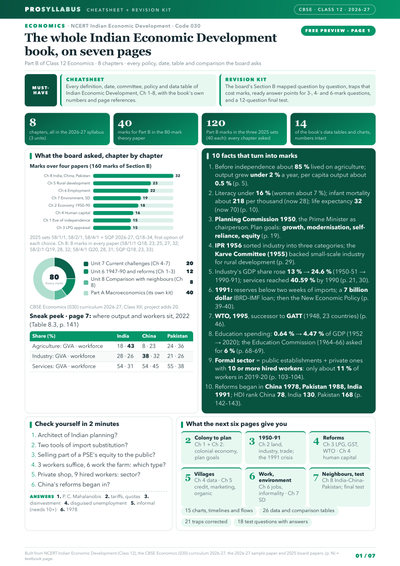
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
Chapter summary
Key ideas & terms
- Cash Flow Statement
- A statement showing the inflows and outflows of cash and cash equivalents during a period, classified into operating, investing and financing activities.
- Cash Equivalents
- Short-term, highly liquid investments readily convertible into known amounts of cash with insignificant risk of change in value.
- Operating Activities
- The principal revenue-producing activities of an enterprise and other activities that are not investing or financing.
- Investing Activities
- Activities relating to the acquisition and disposal of long-term assets and investments.
- Financing Activities
- Activities that change the size and composition of the owners' capital and borrowings of the enterprise.
- AS-3
- Accounting Standard 3 on Cash Flow Statement, notified under the Companies Act 2013, which governs the preparation of the statement.
Extra questions & answers
What is a cash flow statement?
It is a statement that shows the inflows and outflows of cash and cash equivalents over a period, classified into operating, investing and financing activities.
Under which standard is the cash flow statement prepared?
It is prepared in accordance with Accounting Standard 3 (AS-3), notified under Section 133 of the Companies Act 2013.
Into which three activities are cash flows classified?
Operating activities, investing activities and financing activities.
What are operating activities?
The principal revenue-producing activities of the enterprise and other activities that are not investing or financing activities.
What are investing activities?
Activities relating to the acquisition and disposal of long-term assets and investments, such as purchase or sale of fixed assets.
What are financing activities?
Activities that change the size and composition of the owners' capital and borrowings, such as issue of shares or repayment of loans.
Name the two methods of computing cash flow from operating activities.
The direct method and the indirect method.
What does the indirect method start with?
It starts with net profit before tax and adjusts it for non-cash and non-operating items and for changes in working capital.
What are cash equivalents?
Short-term, highly liquid investments that are readily convertible into known amounts of cash and subject to insignificant risk of change in value.
Why is a cash flow statement useful?
It helps users assess the enterprise's ability to generate cash and cash equivalents and to evaluate its liquidity and solvency.