Accounting for Partnership: Basic Concepts — Class 12 Accountancy
Accountancy Part I · Chapter 1
CBSE Class 12 community
View all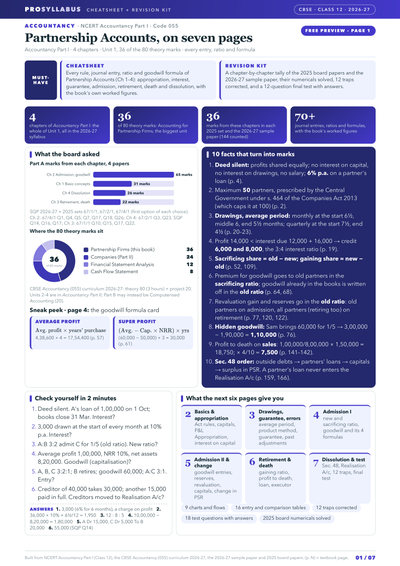
 9
- Accountancy
- Business Studies
- + 3 more
- Accountancy
 8
- Mathematics
- Physics
- + 3 more
- Physics
- Chemistry
- + 3 more
- Physics
 3
- History
 2
- हिंदी
 2
- Mathematics
 2
- Sociology
 2
- Economics
 2
- Home Science
 2
- اردو
- Urdu Elective
 3
- Geography
 2
- Flamingo
- Vistas
 2
- Political Science
 2
- Chemistry
 2
- Business Studies
 2
- हिंदी
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
- Space weighted by unit marks
- Charts from the book's own data
- Traps corrected
Chapter summary
Key ideas & terms
- Partnership
- The relation between persons who have agreed to share the profits of a business carried on by all or any of them acting for all (Section 4, Indian Partnership Act 1932).
- Partnership Deed
- A written agreement among partners stating the terms governing capital, profit sharing, interest, salary and other matters.
- Mutual Agency
- The principle that each partner is both principal and agent, able to bind the firm and the other partners by acts done in the course of business.
- Profit and Loss Appropriation Account
- An extension of the Profit and Loss Account that distributes net profit among partners after charging appropriations such as interest on capital and salary.
- Fixed Capital Method
- A method in which each partner keeps a fixed capital account and a separate current account for adjustments like interest, salary and drawings.
- Interest on Drawings
- A charge made on amounts withdrawn by a partner for personal use, credited to the firm and debited to the partner.
Extra questions & answers
What is the maximum number of partners allowed in a firm?
The Central Government, under Section 464 of the Companies Act 2013, has prescribed a maximum of 50 partners in a firm; the minimum is two.
What is a partnership deed?
It is a written document containing the agreed terms and conditions of a partnership, covering profit-sharing ratio, capital, interest, salary and other matters.
In the absence of a partnership deed, how are profits shared?
They are shared equally among all partners, irrespective of capital contribution, because the Indian Partnership Act 1932 applies.
What rate of interest is allowed on a partner's loan when the deed is silent?
Interest is allowed at 6% per annum on a loan advanced by a partner to the firm.
Distinguish fixed and fluctuating capital methods.
Under the fixed method, capital stays unchanged and a separate current account records adjustments; under the fluctuating method, all adjustments pass through a single capital account so its balance changes each year.
Why is the Profit and Loss Appropriation Account prepared?
To show how net profit is appropriated among partners through interest on capital, salary, commission, interest on drawings and the final share of profit.
How is interest on drawings treated?
It is an income for the firm; the partner's capital (or current) account is debited and interest on drawings is credited to the appropriation account.
What is meant by guarantee of profit to a partner?
It is an assurance of a minimum amount of profit to a partner; any deficiency is borne by the guaranteeing partner or partners in the agreed ratio.
When is a past adjustment entry passed?
When errors or omissions in interest on capital, salary or profit sharing of earlier years are discovered, a single adjusting entry corrects the partners' accounts.
What is mutual agency in partnership?
It means every partner can bind the firm and other partners by acts done in the ordinary course of the firm's business, acting as both principal and agent.