Checked 28 October 2026. Answers follow the rules issued up to 30 June 2026, the cut-off IIBF uses for exams from September 2026 to February 2027. उत्तर 30 जून 2026 तक जारी नियमों पर आधारित हैं; यह IIBF की दिसंबर 2026 परीक्षा की कट-ऑफ तारीख है।
इस पेज पर IIBF की ऋण वसूली एजेंट (Debt Recovery Agent, DRA) परीक्षा के चारों मॉड्यूल से 30 हल किए हुए प्रश्न हैं: मॉड्यूल A से 7, B से 8, C से 11 और D से 4। हर प्रश्न पहले हिंदी में है, चार विकल्पों, सही उत्तर और व्याख्या के साथ। उसके नीचे "English version" खोलकर वही प्रश्न अंग्रेज़ी में पढ़ सकते हैं।
ज़रूरी बात: ये हमारे अपने अभ्यास प्रश्न हैं, जो इसी पेज के लिए लिखे गए हैं; ये पेड मॉक टेस्ट के प्रश्न नहीं हैं। ये IIBF के प्रश्न नहीं हैं और IIBF के किसी प्रश्नपत्र से नहीं लिए गए। IIBF अपने प्रश्नों को अपनी बौद्धिक संपत्ति मानता है और उन्हें किसी से साझा नहीं करता। हमने ये प्रश्न RBI के निर्देशों, कानूनों (NI Act, SARFAESI Act आदि) और IIBF के 2024 सिलेबस के आधार पर लिखे हैं। जहाँ लागू है, व्याख्या में RBI निर्देश का पैरा या कानून की धारा दी गई है; बैंकिंग के सामान्य सिद्धांत और हमारी व्यावहारिक सलाह RBI के नियम नहीं हैं।
In English: 30 solved practice questions for the IIBF Debt Recovery Agents exam, grouped by module, Hindi first with an English version under each. These are our own practice questions written for this page, not the paid mock-test questions, not IIBF questions; IIBF does not share its question bank. Where it applies, the explanation gives the RBI paragraph or the section of the Act; general banking principles and our practical advice are not RBI rules.
ProSyllabus एक स्वतंत्र पढ़ाई की वेबसाइट है। इसका IIBF (इंडियन इंस्टीट्यूट ऑफ बैंकिंग एंड फाइनेंस), RBI या किसी बैंक से कोई संबंध नहीं है। इस पेज के नियम पेज के अंत में दिए गए आधिकारिक दस्तावेज़ों से लिए गए हैं; जहाँ लागू है, वहाँ पैरा या धारा भी दी गई है। बैंकिंग के सामान्य सिद्धांत और हमारी व्यावहारिक सलाह RBI के नियम नहीं हैं।
ProSyllabus is an independent study site. It is not connected with the Indian Institute of Banking & Finance (IIBF), the Reserve Bank of India or any bank, and nothing here is an IIBF document. The rules on this page come from the official documents listed at the foot of the page, with the paragraph or section number where one applies; general banking principles and our own practical advice are not RBI rules.
परीक्षा की संख्याएँ IIBF Rules & Syllabus 2024 और IIBF के DRA पेज से। Exam figures from IIBF Rules & Syllabus 2024 and the IIBF DRA page.
मुफ़्तविषय: Module A · Banking basics · Module D · NBFCs · Module C · Recovery conduct and skills · Module B · Loans and recovery law
IIBF DRA Mock Test · Free sample (English)
असली परीक्षा की तरह तय समय में 5 प्रश्नों के उत्तर दें। इसके बाद हर प्रश्न का सही उत्तर, उसका कारण और उस पर लगा आपका समय दिखेगा। लगभग 6 मिनट · मुफ़्त · साइन-इन की ज़रूरत नहीं।
5 प्रश्न हल करने हैं
अभी शुरू करेंलगभग 6 minयह मुफ़्त है · साइन-इन की ज़रूरत नहीं
आपके परिणाम में दिखेगा कि हर प्रश्न पर कितना समय लगा।
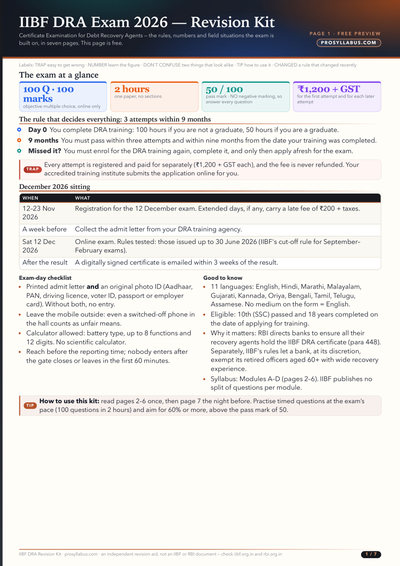
DRA परीक्षा का पैटर्न (IIBF नियम 2024)
| विषय | IIBF का नियम |
|---|---|
| प्रश्न | 100 वस्तुनिष्ठ बहुविकल्पीय प्रश्न (MCQ) |
| अंक | कुल 100 अंक |
| समय | 2 घंटे |
| तरीका | केवल ऑनलाइन, परीक्षा केंद्र पर |
| नकारात्मक अंक | नहीं, गलत उत्तर पर अंक नहीं कटते |
| पास होने के अंक | 100 में से 50 |
| प्रयास | प्रशिक्षण पूरा होने की तारीख से 9 महीने में 3 प्रयास; फिर से प्रशिक्षण के बाद ही नई परीक्षा |
| फीस | हर प्रयास के लिए ₹1,200 + लागू GST (IIBF DRA पेज); 2024 के नियमों के अनुसार सुविधा शुल्क (convenience charges) और लागू टैक्स भी लगते हैं; फीस वापस नहीं होती |
| भाषा | हिंदी, अंग्रेज़ी और 9 अन्य भाषाएँ; फॉर्म में भाषा न लिखी हो तो अंग्रेज़ी मानी जाती है |
| मॉड्यूल-वार प्रश्न | IIBF कोई बँटवारा प्रकाशित नहीं करता |
फीस, तारीखों और 3 प्रयास वाले नियम की पूरी जानकारी अंग्रेज़ी में हमारी गाइड में है: IIBF DRA exam 2026: pattern, fee, 3-attempt rule and dates। अगली निर्धारित परीक्षा शनिवार, 14 नवंबर 2026 को है, पर उसका पंजीकरण 26 अक्टूबर को बंद हो चुका है। जिस परीक्षा का पंजीकरण अभी खुलना है, वह शनिवार, 12 दिसंबर 2026 को है; उसका पंजीकरण 12 से 23 नवंबर 2026 तक आपकी ट्रेनिंग एजेंसी करती है।
इन प्रश्नों का उपयोग कैसे करें / How to use these questions
चार कदम
- पहले खुद जवाब दें। सही उत्तर वाली हरी पट्टी को हाथ या कागज़ से ढक लें, विकल्प चुनें, फिर मिलाएँ।
- व्याख्या ज़रूर पढ़ें। जहाँ लागू है, व्याख्या में RBI निर्देश का पैरा या कानून की धारा दी गई है। परीक्षा में वही नियम दूसरे शब्दों में पूछा जा सकता है।
- जिन संख्याओं या समय-सीमाओं में गलती हुई, उन्हें लिखें। जैसे सुबह 8 बजे, शाम 7 बजे, 60 दिन, 45 दिन, 20 लाख। आखिर में दी गई "मुख्य संख्याएँ" तालिका से रोज़ मिलाएँ।
- उसी भाषा में अभ्यास करें जिसमें परीक्षा देंगे। अगर परीक्षा अंग्रेज़ी में देनी है, तो "English version" खोलकर वही प्रश्न अंग्रेज़ी में भी हल करें।
In English: answer before you look, read every explanation, note the numbers you miss, and practise in the language you will write the exam in.
सही उत्तर हर बार पहला विकल्प नहीं है: 30 प्रश्नों में सही उत्तर A पर 8, B पर 8, C पर 7 और D पर 7 बार है। The correct answers are spread across A, B, C and D.
यह बँटवारा हमारा है, IIBF का नहीं। IIBF 100 प्रश्नों का मॉड्यूल-वार बँटवारा प्रकाशित नहीं करता। Our split for this page; IIBF publishes no per-module split.
मॉड्यूल A: बैंकिंग की बुनियादी बातें (7 प्रश्न) / Module A: Basics of Banking
यह मॉड्यूल बैंकिंग की नींव है: KYC, ग्राहक और बैंक का रिश्ता, चेक और NI Act, और जमा बीमा। इन सवालों में ज़्यादातर संख्याएँ हैं (5 साल, 30 दिन, 15 दिन, 2 साल, 5 लाख), इसलिए इन्हें याद करना ज़रूरी है।
The foundation: KYC, the banker-customer relationship, cheques under the Negotiable Instruments Act, and deposit insurance. Most of these questions turn on a number, so learn the figures.
प्रश्न 1 · Question 1 · Module A
RBI के KYC निर्देशों के अनुसार इनमें से कौन-सा "ऑफिशियली वैलिड डॉक्यूमेंट" (OVD) है?
- A. कंपनी का पहचान-पत्र (ID कार्ड)
- B. राशन कार्ड
- C. ड्राइविंग लाइसेंस
- D. PAN कार्ड
सही उत्तर: C. ड्राइविंग लाइसेंस
व्याख्या: RBI KYC निर्देशों के पैरा 5 में OVD की सूची है: पासपोर्ट, ड्राइविंग लाइसेंस, आधार नंबर होने का प्रमाण, वोटर ID, राज्य सरकार के अधिकारी द्वारा हस्ताक्षरित NREGA जॉब कार्ड, और नाम-पते वाला राष्ट्रीय जनसंख्या रजिस्टर (NPR) का पत्र। राशन कार्ड, PAN कार्ड या कंपनी का ID कार्ड इस सूची में नहीं है।
English version
Q1. Under RBI's KYC Directions, which of these is an Officially Valid Document (OVD)?
A. Company identity card · B. Ration card · C. Driving licence · D. PAN card
Answer: C. Driving licence. The OVD list in para 5 of the RBI KYC Directions is: passport, driving licence, proof of possession of Aadhaar number, Voter ID, NREGA job card signed by a State Government officer, and the National Population Register (NPR) letter with name and address. A ration card, PAN card or company ID card is not on it.
प्रश्न 2 · Question 2 · Module A
RBI KYC निर्देशों के अनुसार बैंक को ग्राहक के साथ हुए लेन-देन का रिकॉर्ड कम से कम कितने समय तक रखना होता है?
- A. खाता बंद होने के बाद कम से कम 1 साल
- B. लेन-देन की तारीख से कम से कम 3 साल
- C. लेन-देन की तारीख से कम से कम 8 साल
- D. लेन-देन की तारीख से कम से कम 5 साल
सही उत्तर: D. लेन-देन की तारीख से कम से कम 5 साल
व्याख्या: RBI KYC निर्देश पैरा 50(1): बैंक ग्राहक के साथ हुए हर लेन-देन का रिकॉर्ड लेन-देन की तारीख से कम से कम पाँच साल तक रखता है।
English version
Q2. Under the RBI KYC Directions, for how long must a bank keep the records of its transactions with a customer?
A. At least 1 year after the account is closed · B. At least 3 years from the date of the transaction · C. At least 8 years from the date of the transaction · D. At least 5 years from the date of the transaction
Answer: D. At least 5 years from the date of the transaction. Para 50(1) of the RBI KYC Directions: the bank keeps all records of transactions with the customer for at least five years from the date of the transaction.
प्रश्न 3 · Question 3 · Module A
NI Act (Negotiable Instruments Act) की धारा 6 के अनुसार चेक एक बिल ऑफ एक्सचेंज है जो किस पर लिखा जाता है और माँगने पर देय होता है?
- A. चेक काटने वाले के नियोक्ता (employer) पर
- B. पास के डाकघर पर
- C. चेक काटने वाले के बताए किसी भी व्यक्ति पर
- D. एक तय (specified) बैंक पर
सही उत्तर: D. एक तय (specified) बैंक पर
व्याख्या: NI Act की धारा 6: चेक वह बिल ऑफ एक्सचेंज है जो किसी तय बैंक पर लिखा हो और माँगने पर (on demand) देय हो। इसमें ट्रंकेटेड चेक की इमेज और इलेक्ट्रॉनिक चेक भी आते हैं।
English version
Q3. Under section 6 of the Negotiable Instruments Act, a cheque is a bill of exchange drawn on whom, payable on demand?
A. The employer of the drawer · B. The nearest post office · C. Any person the drawer names · D. A specified banker
Answer: D. A specified banker. Section 6 of the NI Act defines a cheque as a bill of exchange drawn on a specified banker and payable on demand (it includes a truncated cheque image and a cheque in electronic form).
प्रश्न 4 · Question 4 · Module A
उधारकर्ता का EMI वाला चेक खाते में पैसा न होने से बाउंस हो गया। NI Act की धारा 138 के अनुसार बैंक से इसकी जानकारी मिलने के कितने दिन के अंदर लेनदार को लिखित डिमांड नोटिस भेजना होता है?
- A. 15 दिन
- B. 30 दिन
- C. 60 दिन
- D. 90 दिन
सही उत्तर: B. 30 दिन
व्याख्या: धारा 138 का प्रावधान (b): चेक बाउंस की जानकारी मिलने के तीस दिन के अंदर लिखित नोटिस देकर पैसा माँगना होता है। 15 दिन वह समय है जो नोटिस मिलने की तारीख से चेक काटने वाले को भुगतान के लिए मिलता है।
English version
Q4. A borrower's EMI cheque bounces for lack of funds. Under section 138 of the NI Act, within how many days of hearing about it from the bank must the lender send a written demand notice?
A. 15 days · B. 30 days · C. 60 days · D. 90 days
Answer: B. 30 days. Section 138 proviso (b): the payee must demand payment by a written notice within thirty days of receiving the information of dishonour from the bank. The 15 days is the time the drawer then gets to pay, counted from receiving the notice.
प्रश्न 5 · Question 5 · Module A
NI Act की धारा 138 के तहत चेक बाउंस के अपराध में अधिकतम सज़ा क्या है?
- A. 7 साल तक जेल और साथ में चेक की रकम जितना जुर्माना भी
- B. 2 साल तक जेल, या चेक की रकम के दोगुने तक जुर्माना, या दोनों
- C. केवल चेक की रकम तक जुर्माना; इस अपराध में जेल की सज़ा नहीं होती
- D. 6 महीने तक जेल, या चेक की रकम तक जुर्माना, या दोनों
सही उत्तर: B. 2 साल तक जेल, या चेक की रकम के दोगुने तक जुर्माना, या दोनों
व्याख्या: NI Act धारा 138: दो साल तक की जेल, या चेक की रकम के दोगुने तक जुर्माना, या दोनों।
English version
Q5. What is the maximum punishment for a cheque bounce offence under section 138 of the NI Act?
A. Jail up to 7 years, and a fine equal to the cheque amount, both together · B. Jail up to 2 years, or fine up to twice the cheque amount, or both · C. Only a fine up to the cheque amount; there is no jail for this offence · D. Jail up to 6 months, or fine up to the cheque amount, or both
Answer: B. Jail up to 2 years, or fine up to twice the cheque amount, or both. Section 138 of the NI Act: imprisonment for a term up to two years, or a fine up to twice the amount of the cheque, or both.
प्रश्न 6 · Question 6 · Module A
जब बैंक किसी ग्राहक को लोन देता है, तब बैंक और ग्राहक का संबंध क्या होता है?
- A. पट्टादाता और पट्टेदार: बैंक पट्टादाता (lessor) है
- B. देनदार और लेनदार: बैंक देनदार (debtor) है
- C. बेलर और बेली: बैंक बेली (bailee) है
- D. लेनदार और देनदार: बैंक लेनदार (creditor) है
सही उत्तर: D. लेनदार और देनदार: बैंक लेनदार (creditor) है
व्याख्या: लोन में पैसा बैंक देता है, इसलिए बैंक लेनदार (creditor) और उधारकर्ता देनदार (debtor) होता है। जमा (deposit) में उल्टा होता है; सामान सुरक्षित रखने में बेलर-बेली और लॉकर में पट्टादाता-पट्टेदार का संबंध होता है।
English version
Q6. When a bank gives a loan to a customer, what is the banker-customer relationship?
A. Lessor and lessee: the bank is the lessor · B. Debtor and creditor: the bank is the debtor · C. Bailor and bailee: the bank holds it as bailee · D. Creditor and debtor: the bank is the creditor
Answer: D. Creditor and debtor: the bank is the creditor. In a loan the bank lends money, so the bank is the creditor and the borrower is the debtor. In a deposit it is the other way round; safe custody is bailor-bailee and a locker is lessor-lessee.
प्रश्न 7 · Question 7 · Module A
DICGC से बीमित बैंक डूबने पर DICGC जमाकर्ता के कितने पैसे तक का बीमा देता है?
- A. हर बैंक में एक जमाकर्ता के 10 लाख रुपये तक
- B. हर ब्रांच में हर खाते के 5 लाख रुपये तक
- C. हर बैंक में एक जमाकर्ता के 1 लाख रुपये तक
- D. हर बैंक में एक जमाकर्ता के 5 लाख रुपये तक
सही उत्तर: D. हर बैंक में एक जमाकर्ता के 5 लाख रुपये तक
व्याख्या: 4 फरवरी 2020 से DICGC एक बैंक में एक जमाकर्ता के 5 लाख रुपये तक (मूलधन और ब्याज मिलाकर) का बीमा देता है। एक ही हैसियत और अधिकार से रखी जमा पर, उस बैंक की सभी ब्रांचों के खाते मिलाकर गिने जाते हैं।
English version
Q7. Up to how much does DICGC insure a depositor's money if a DICGC-insured bank fails?
A. Rs 10 lakh per depositor in each bank · B. Rs 5 lakh per account in each branch · C. Rs 1 lakh per depositor in each bank · D. Rs 5 lakh per depositor in each bank
Answer: D. Rs 5 lakh per depositor in each bank. Since 4 February 2020 DICGC covers up to Rs 5 lakh per depositor per bank, principal and interest together, for deposits held in the same right and capacity, counted across all branches of that bank.
मुफ़्तविषय: Module A · Banking basics · Module D · NBFCs · Module C · Recovery conduct and skills · Module B · Loans and recovery law
IIBF DRA Mock Test · Free sample (English)
असली परीक्षा की तरह तय समय में 5 प्रश्नों के उत्तर दें। इसके बाद हर प्रश्न का सही उत्तर, उसका कारण और उस पर लगा आपका समय दिखेगा। लगभग 6 मिनट · मुफ़्त · साइन-इन की ज़रूरत नहीं।
5 प्रश्न हल करने हैं
अभी शुरू करेंलगभग 6 minयह मुफ़्त है · साइन-इन की ज़रूरत नहीं
आपके परिणाम में दिखेगा कि हर प्रश्न पर कितना समय लगा।
मॉड्यूल B: लोन और वसूली के कानूनी पहलू (8 प्रश्न) / Module B: Products and Legal Aspects of Recovery
यह मॉड्यूल लोन और वसूली के कानून का है: NPA कब बनता है, सिक्योरिटी के प्रकार, SARFAESI Act का नोटिस और DRT में आवेदन, DRT की सीमा, और लोक अदालत। यहाँ हर कानून की धारा और दिनों की गिनती पर ध्यान दें।
Loans and the law of recovery: when a loan becomes an NPA, types of charge, the SARFAESI notice and the application to the DRT, the DRT threshold and Lok Adalat. Watch the section numbers and the day counts.
प्रश्न 8 · Question 8 · Module B
साधारण (गैर-कृषि) टर्म लोन NPA (नॉन-परफॉर्मिंग एसेट) कब बनता है, जब उसका ब्याज या किस्त कितने समय से ज़्यादा बकाया रहे?
- A. 90 दिन से ज़्यादा
- B. 30 दिन से ज़्यादा
- C. 180 दिन से ज़्यादा
- D. 60 दिन से ज़्यादा
सही उत्तर: A. 90 दिन से ज़्यादा
व्याख्या: RBI IRACP निर्देश पैरा 42(1): टर्म लोन का ब्याज और/या मूलधन की किस्त 90 दिन से ज़्यादा बकाया रहे तो खाता NPA हो जाता है।
English version
Q8. An ordinary (non-agricultural) term loan becomes a non-performing asset (NPA) when its interest or instalment stays overdue for:
A. More than 90 days · B. More than 30 days · C. More than 180 days · D. More than 60 days
Answer: A. More than 90 days. RBI IRACP Directions para 42(1): a term loan is an NPA when interest and/or an instalment of principal remains overdue for more than 90 days.
प्रश्न 9 · Question 9 · Module B
एक उधारकर्ता का लोन NPA है। उसने 5 बकाया EMI में से 2 भर दीं। बैंक खाते को "स्टैंडर्ड" कब कर सकता है?
- A. जब ब्याज और मूलधन का पूरा बकाया चुका दिया जाए
- B. जैसे ही वह बकाया EMI में से कम से कम आधी भर दे
- C. तुरंत, क्योंकि कोई भी आंशिक भुगतान खाते को ठीक कर देता है
- D. जब वह बाकी EMI के पोस्ट-डेटेड चेक दे दे
सही उत्तर: A. जब ब्याज और मूलधन का पूरा बकाया चुका दिया जाए
व्याख्या: RBI IRACP निर्देश पैरा 69: NPA खाता तभी स्टैंडर्ड हो सकता है जब उधारकर्ता ब्याज और मूलधन का पूरा बकाया चुका दे। अगर उसके उस बैंक से एक से ज़्यादा लोन हैं, तो उस बैंक की सभी ऋण सुविधाओं का ब्याज और मूलधन का पूरा अतिदेय बकाया चुकाना होगा (पैरा 71)। आंशिक भुगतान अच्छा है, पर उससे खाता स्टैंडर्ड नहीं होता।
English version
Q9. A borrower whose loan is an NPA pays 2 of his 5 overdue EMIs. When can the bank upgrade the account to "standard"?
A. Only when the entire arrears of interest and principal are paid · B. As soon as he has paid at least half of the overdue EMIs · C. At once, because any part payment upgrades the account · D. When he hands over post-dated cheques for the remaining EMIs
Answer: A. Only when the entire arrears of interest and principal are paid. RBI IRACP Directions para 69: an NPA may be upgraded to standard only if the borrower pays the entire arrears of interest and principal. If he has more than one loan from the bank, the arrears of all of them must be paid (para 71). A part payment is welcome but does not upgrade it.
प्रश्न 10 · Question 10 · Module B
उधारकर्ता ने बाइक लोन लिया। बाइक उधारकर्ता के कब्ज़े में रहती है, और बैंक का उस पर सिक्योरिटी के रूप में चार्ज होता है। इस चार्ज को क्या कहते हैं?
- A. मॉर्गेज (बंधक)
- B. हाइपोथिकेशन (दृष्टिबंधक)
- C. प्लेज (गिरवी)
- D. लियन (ग्रहणाधिकार)
सही उत्तर: B. हाइपोथिकेशन (दृष्टिबंधक)
व्याख्या: हाइपोथिकेशन में चल संपत्ति (जैसे गाड़ी) उधारकर्ता के पास ही रहती है और बैंक के पक्ष में चार्ज होती है। प्लेज में सामान बैंक के कब्ज़े में चला जाता है; मॉर्गेज में लोन की सुरक्षा के लिए किसी तय अचल संपत्ति (मकान, ज़मीन) में हित (interest) बैंक को हस्तांतरित किया जाता है।
English version
Q10. A borrower takes a bike loan. The bike stays with him, but it is charged to the bank as security. What is this charge called?
A. Mortgage · B. Hypothecation · C. Pledge · D. Lien
Answer: B. Hypothecation. In hypothecation the movable asset stays with the borrower while it is charged to the lender. In a pledge the goods go into the lender's possession; a mortgage transfers an interest in specific immovable property (house, land) to secure the loan.
प्रश्न 11 · Question 11 · Module B
SARFAESI Act की धारा 13(2) के डिमांड नोटिस में उधारकर्ता को बकाया चुकाने के लिए कितने दिन मिलते हैं?
- A. 15 दिन
- B. 90 दिन
- C. 60 दिन
- D. 30 दिन
सही उत्तर: C. 60 दिन
व्याख्या: SARFAESI Act धारा 13(2): बैंक लिखित नोटिस देकर 60 दिन में पूरा बकाया चुकाने को कहता है। न चुकाने पर बैंक धारा 13(4) के तहत कार्रवाई कर सकता है।
English version
Q11. Under section 13(2) of the SARFAESI Act, the bank's demand notice gives the borrower how many days to pay the dues?
A. 15 days · B. 90 days · C. 60 days · D. 30 days
Answer: C. 60 days. SARFAESI Act s.13(2): the secured creditor asks the borrower in writing to discharge the liabilities in full within 60 days of the notice. If he does not, the bank may act under s.13(4).
प्रश्न 12 · Question 12 · Module B
बैंक ने SARFAESI Act की धारा 13(4) के तहत उधारकर्ता की संपत्ति पर कब्ज़ा ले लिया। धारा 17 के तहत उधारकर्ता कितने दिन के अंदर DRT में आवेदन कर सकता है?
- A. 60 दिन
- B. 15 दिन
- C. 45 दिन
- D. 30 दिन
सही उत्तर: C. 45 दिन
व्याख्या: SARFAESI Act धारा 17: धारा 13(4) की कार्रवाई से पीड़ित (aggrieved) कोई भी व्यक्ति कार्रवाई की तारीख से 45 दिन के अंदर ऋण वसूली अधिकरण (DRT) में आवेदन कर सकता है।
English version
Q12. A bank has taken possession of a borrower's property under section 13(4) of the SARFAESI Act. Under section 17, the borrower can apply to the DRT within:
A. 60 days · B. 15 days · C. 45 days · D. 30 days
Answer: C. 45 days. SARFAESI Act s.17: any person aggrieved by the measures taken under s.13(4) may apply to the Debts Recovery Tribunal within 45 days from the date the measures were taken.
प्रश्न 13 · Question 13 · Module B
बैंक ऋण वसूली अधिकरण (DRT) में वसूली का केस तब कर सकता है जब कर्ज़ कम से कम कितना हो?
- A. 10 लाख रुपये
- B. 1 लाख रुपये
- C. 20 लाख रुपये
- D. 1 करोड़ रुपये
सही उत्तर: C. 20 लाख रुपये
व्याख्या: Recovery of Debts and Bankruptcy Act, 1993 के तहत DRT 20 लाख रुपये और उससे ज़्यादा के कर्ज़ सुनता है (वित्त मंत्रालय अधिसूचना S.O. 4312(E), 6 सितंबर 2018)। छोटे कर्ज़ सिविल कोर्ट या दूसरे मंचों पर जाते हैं।
English version
Q13. A bank can file a recovery case in the Debts Recovery Tribunal (DRT) when the debt is at least:
A. Rs 10 lakh · B. Rs 1 lakh · C. Rs 20 lakh · D. Rs 1 crore
Answer: C. Rs 20 lakh. Under the Recovery of Debts and Bankruptcy Act, 1993 the DRT hears debts of Rs 20 lakh and above (Finance Ministry notification S.O. 4312(E), 6 September 2018). Smaller debts go to civil courts or other forums.
प्रश्न 14 · Question 14 · Module B
बैंक और उधारकर्ता ने लोक अदालत में लोन का झगड़ा सुलझा लिया। उस फैसले (award) के बारे में क्या सही है?
- A. यह सिविल कोर्ट की डिक्री माना जाता है और इसकी अपील नहीं होती
- B. यह बैंक पर लागू होता है, पर उधारकर्ता इसे फिर भी मना कर सकता है
- C. यह तभी मान्य होता है जब DRT इसे लिखकर मंज़ूरी दे
- D. दोनों में से कोई भी इसके खिलाफ हाई कोर्ट में अपील कर सकता है
सही उत्तर: A. यह सिविल कोर्ट की डिक्री माना जाता है और इसकी अपील नहीं होती
व्याख्या: विधिक सेवा प्राधिकरण अधिनियम (Legal Services Authorities Act), 1987 की धारा 21: लोक अदालत का फैसला सिविल कोर्ट की डिक्री माना जाता है, सभी पक्षों पर अंतिम और बाध्यकारी होता है, और इसके खिलाफ कोई अपील नहीं होती।
English version
Q14. A bank and a borrower settle a loan dispute in a Lok Adalat. What is true of the award?
A. It counts as a civil court decree and no appeal lies · B. It binds the bank but the borrower may still refuse it · C. It is valid only after the DRT approves it in writing · D. Either side may appeal against it in the High Court
Answer: A. It counts as a civil court decree and no appeal lies. Legal Services Authorities Act, 1987, s.21: a Lok Adalat award is deemed a decree of a civil court, is final and binding on all parties, and no appeal lies against it.
प्रश्न 15 · Question 15 · Module B
SARFAESI Act की धारा 31 के अनुसार यह कानून इनमें से किस पर बने प्रतिभूति हित (security interest) पर लागू नहीं होता?
- A. फैक्ट्री की इमारत
- B. खेती की ज़मीन
- C. रहने का फ्लैट
- D. बाज़ार की दुकान
सही उत्तर: B. खेती की ज़मीन
व्याख्या: SARFAESI Act धारा 31 में वे मामले दिए हैं जिन पर यह कानून लागू नहीं होता; उनमें खेती की ज़मीन पर बना प्रतिभूति हित (security interest) भी है। इसलिए बैंक SARFAESI से खेती की ज़मीन पर कब्ज़ा नहीं ले सकता।
English version
Q15. Section 31 of the SARFAESI Act says the Act does NOT apply to a security interest created on which of these?
A. A factory building · B. Agricultural land · C. A residential flat · D. A shop in a market
Answer: B. Agricultural land. SARFAESI Act s.31 lists cases where the Act does not apply; one of them is any security interest created in agricultural land. So a bank cannot use SARFAESI to take possession of farm land.
मॉड्यूल C: वसूली में एजेंट की भूमिका और सॉफ्ट स्किल्स (11 प्रश्न) / Module C: Role in Loan Recovery and Soft Skills
यह मॉड्यूल आपके रोज़ के काम का है: RBI के रिकवरी एजेंट नियम (कॉल का समय, नोटिस और पहचान-पत्र, कॉल रिकॉर्डिंग, आम तौर पर शिकायत का निपटारा होने तक केस एजेंसी को न भेजना) और फील्ड की आम स्थितियाँ। फील्ड वाले सवालों में सही जवाब वह है जो नियम मानता है और शांत रहता है; शक हो तो बैंक से पूछें।
Your daily work: RBI’s recovery-agent rules (calling hours, notice and ID, call recording, normally no referral to an agency until a complaint is disposed of) and field situations. In a field question, the right answer follows the rule and stays calm; when in doubt, check with the bank.
प्रश्न 16 · Question 16 · Module C
माइक्रोफाइनेंस को छोड़कर बैंक के बकाया लोन की वसूली के लिए RBI उधारकर्ता को कब कॉल करने की इजाज़त नहीं देता?
- A. सुबह 9 बजे से पहले और शाम 6 बजे के बाद
- B. सुबह 8 बजे से पहले और शाम 7 बजे के बाद
- C. सुबह 7 बजे से पहले और रात 9 बजे के बाद
- D. सुबह 10 बजे से पहले और शाम 5 बजे के बाद
सही उत्तर: B. सुबह 8 बजे से पहले और शाम 7 बजे के बाद
व्याख्या: RBI रिस्पॉन्सिबल बिज़नेस कंडक्ट निर्देश पैरा 445: बकाया लोन की वसूली के लिए सुबह 8:00 बजे से पहले और शाम 7:00 बजे के बाद कॉल नहीं कर सकते। सुबह 9 से शाम 6 की सीमा माइक्रोफाइनेंस लोन के लिए है (पैरा 410)।
English version
Q16. For an overdue bank loan that is not a microfinance loan, RBI does not allow recovery calls to the borrower:
A. Before 9 a.m. and after 6 p.m. · B. Before 8 a.m. and after 7 p.m. · C. Before 7 a.m. and after 9 p.m. · D. Before 10 a.m. and after 5 p.m.
Answer: B. Before 8 a.m. and after 7 p.m.. RBI Responsible Business Conduct Directions para 445 bars calling the borrower before 8:00 a.m. and after 7:00 p.m. for recovery of overdue loans. The 9 a.m. to 6 p.m. limit is for microfinance loans (para 410).
प्रश्न 17 · Question 17 · Module C
वसूली के बीच में बैंक ने केस नई रिकवरी एजेंसी को दे दिया। RBI के नियम क्या कहते हैं?
- A. बैंक उधारकर्ता को बताता है; नया एजेंट नोटिस, अधिकार-पत्र और ID साथ रखता है
- B. नया एजेंट सिर्फ अपनी एजेंसी का विज़िटिंग कार्ड और लोन खाता नंबर साथ रखता है
- C. कुछ नया नहीं; पुराना एजेंट ही उधारकर्ता को बदलाव के बारे में बता देता है
- D. नई एजेंसी काम शुरू करे, उससे पहले उधारकर्ता को सहमति-फॉर्म पर साइन करना होगा
सही उत्तर: A. बैंक उधारकर्ता को बताता है; नया एजेंट नोटिस, अधिकार-पत्र और ID साथ रखता है
व्याख्या: RBI RBC निर्देश पैरा 442(3): एजेंसी बदलने पर बैंक उधारकर्ता को सूचना देता है, और नया एजेंट नोटिस, बैंक का अधिकार-पत्र (authorisation letter) और अपना पहचान-पत्र साथ रखता है।
English version
Q17. Midway through recovery, the bank hands a case to a new recovery agency. What do RBI rules require?
A. Bank tells the borrower; new agent carries notice, authorisation letter and ID · B. The new agent carries only his agency visiting card and the loan account number · C. Nothing new; the old agent simply tells the borrower about the change · D. The borrower must first sign a consent form before the new agency can act
Answer: A. Bank tells the borrower; new agent carries notice, authorisation letter and ID. RBI RBC Directions para 442(3): when the agency is changed, the bank notifies the borrower, and the new agent carries the notice and the bank's authorisation letter along with his identity card.
प्रश्न 18 · Question 18 · Module C
एक उधारकर्ता ने बैंक की वसूली प्रक्रिया के बारे में बैंक में शिकायत की है। आम तौर पर बैंक उसके केस का क्या करता है?
- A. शिकायत का निपटारा होने तक केस रिकवरी एजेंट को नहीं भेजता
- B. केस एजेंट को भेजता है, पर हफ्ते में एक बार ही जाने को कहता है
- C. एजेंट के पहली बार जाते ही शिकायत बंद कर देता है
- D. केस तुरंत रिकवरी एजेंट को भेजता है ताकि वसूली में देर न हो
सही उत्तर: A. शिकायत का निपटारा होने तक केस रिकवरी एजेंट को नहीं भेजता
व्याख्या: RBI RBC निर्देश पैरा 442(6): जब तक शिकायत का अंतिम निपटारा न हो, बैंक केस रिकवरी एजेंसी को नहीं भेजता। अगर बैंक को उचित सबूत से पक्का भरोसा हो कि उधारकर्ता लगातार बेबुनियाद या परेशान करने वाली (frivolous / vexatious) शिकायतें कर रहा है, तभी वह शिकायत लंबित रहते हुए भी एजेंटों के ज़रिए वसूली जारी रख सकता है।
English version
Q18. A borrower has lodged a complaint with the bank about its recovery process. Normally, what does the bank do with his case?
A. Holds it back from recovery agents until the complaint is settled · B. Sends it to agents but tells them to visit only once a week · C. Closes the complaint as soon as the agent makes one visit · D. Sends it to recovery agents at once so that recovery is not delayed
Answer: A. Holds it back from recovery agents until the complaint is settled. RBI RBC Directions para 442(6): the bank does not forward the case to recovery agencies till it has finally disposed of the complaint. Only if the bank is convinced, with appropriate proof, that the borrower keeps making frivolous or vexatious complaints may it continue through the agents while the complaint is pending.
प्रश्न 19 · Question 19 · Module C
रिकवरी एजेंट और ग्राहक के बीच फोन कॉल के बारे में RBI के नियम क्या कहते हैं?
- A. कॉल तभी रिकॉर्ड होती है जब ग्राहक खुद ऐसा कहे
- B. कॉल रिकॉर्ड होती है, और ग्राहक को यह बताने जैसी सावधानी रखी जाती है
- C. कॉल चुपचाप रिकॉर्ड होती है, ग्राहक को इसके बारे में कुछ नहीं बताया जाता
- D. ग्राहक की सुरक्षा के लिए कॉल कभी रिकॉर्ड नहीं होती
सही उत्तर: B. कॉल रिकॉर्ड होती है, और ग्राहक को यह बताने जैसी सावधानी रखी जाती है
व्याख्या: RBI RBC निर्देश पैरा 442(4): बैंक यह पक्का करता है कि एजेंट से ग्राहक और ग्राहक से एजेंट की कॉल रिकॉर्ड हों, और उचित सावधानी बरते, जैसे ग्राहक को बताना कि बातचीत रिकॉर्ड हो रही है।
English version
Q19. What do RBI rules say about phone calls between recovery agents and customers?
A. They are recorded only if the customer asks for it · B. They are recorded, with care such as telling the customer · C. They are recorded quietly, without telling the customer · D. They are never recorded, to protect the customer
Answer: B. They are recorded, with care such as telling the customer. RBI RBC Directions para 442(4): the bank ensures calls made by recovery agents to customers, and vice versa, are tape-recorded, and takes reasonable precautions such as telling the customer that the call is being recorded.
प्रश्न 20 · Question 20 · Module C
एक रिकवरी एजेंट उधारकर्ता को परेशान करता है। RBI के नियमों के अनुसार एजेंट के काम की ज़िम्मेदारी किसकी है?
- A. सिर्फ एजेंट की अपनी
- B. सिर्फ उस एजेंसी की जिसने उसे रखा
- C. बैंक की, क्योंकि वह प्रधान (principal) है
- D. IIBF की, जिसने उसे सर्टिफिकेट दिया
सही उत्तर: C. बैंक की, क्योंकि वह प्रधान (principal) है
व्याख्या: RBI RBC निर्देश पैरा 452: बैंक प्रधान (principal) के रूप में अपने एजेंटों के कामों के लिए ज़िम्मेदार है, इसलिए उसे देखना होता है कि एजेंट वसूली के नियम मानें।
English version
Q20. A recovery agent harasses a borrower. Under RBI rules, who is responsible for the agent's actions?
A. Only the agent himself · B. Only the agency that hired him · C. The bank, as the principal · D. The IIBF, which certified him
Answer: C. The bank, as the principal. RBI RBC Directions para 452: the bank, as principal, is responsible for the actions of its agents, so it must make sure they follow the recovery rules.
प्रश्न 21 · Question 21 · Module C
RBI को किसी बैंक के एजेंटों की गलत तरीके से वसूली की लगातार शिकायतें मिल रही हैं। RBI के नियम क्या कार्रवाई की इजाज़त देते हैं?
- A. उसी दिन बैंक का बैंकिंग लाइसेंस रद्द कर देना
- B. कुछ समय के लिए किसी इलाके में बैंक के रिकवरी एजेंट रखने पर रोक
- C. शिकायत करने वाले हर उधारकर्ता के लोन को बट्टे खाते में डाल देना (write off कर देना)
- D. उस राज्य के सभी एजेंटों के IIBF सर्टिफिकेट रद्द कर देना
सही उत्तर: B. कुछ समय के लिए किसी इलाके में बैंक के रिकवरी एजेंट रखने पर रोक
व्याख्या: RBI RBC निर्देश पैरा 453: RBI किसी बैंक पर एक तय इलाके (क्षेत्र या काम के हिसाब से) में सीमित समय के लिए रिकवरी एजेंट रखने पर रोक लगा सकता है, और बार-बार नियम तोड़ने पर रोक बढ़ा सकता है।
English version
Q21. RBI keeps getting complaints of abusive recovery by a bank's agents. What action do RBI rules allow?
A. Cancelling the bank's banking licence on the very same day · B. A ban on the bank using recovery agents in an area for a time · C. Writing off the loans of every single borrower who has complained · D. Cancelling the IIBF certificates of all agents in that state
Answer: B. A ban on the bank using recovery agents in an area for a time. RBI RBC Directions para 453: RBI may ban a bank from engaging recovery agents in a particular area, jurisdictional or functional, for a limited period, and may extend the ban for persistent breach.
प्रश्न 22 · Question 22 · Module C
माइक्रोफाइनेंस लोन की किस्त उस जगह पर ली जाती है जो उधारकर्ता और बैंक ने मिलकर तय की है। फील्ड स्टाफ उधारकर्ता के घर या काम की जगह पर कब जा सकता है?
- A. जब वह लगातार 2 या ज़्यादा बार उस तय जगह पर न आए
- B. जब भी उसके रिश्तेदार या पड़ोसी मान लें कि जाना ज़रूरी है
- C. किसी भी दिन, बस समय सुबह 8 से शाम 7 बजे के बीच हो
- D. तभी जब बैंक उसके खिलाफ कोर्ट में वसूली का केस कर दे
सही उत्तर: A. जब वह लगातार 2 या ज़्यादा बार उस तय जगह पर न आए
व्याख्या: RBI RBC निर्देश पैरा 409: वसूली दोनों की तय की हुई जगह पर होती है; फील्ड स्टाफ घर या काम की जगह पर तभी जा सकता है जब उधारकर्ता लगातार दो या ज़्यादा बार वहाँ न आए।
English version
Q22. Microfinance loan repayments are collected at a place agreed by the borrower and the bank. When may field staff go to the borrower's home or workplace instead?
A. If he fails to come to that place on 2 or more successive occasions · B. Whenever his relatives or neighbours agree that a visit is needed · C. On any day, as long as the visit is between 8 a.m. and 7 p.m. · D. Only after the bank has filed a recovery case against him in court
Answer: A. If he fails to come to that place on 2 or more successive occasions. RBI RBC Directions para 409: recovery is made at a designated or central place agreed by both; field staff may go to the borrower's residence or work only if he fails to appear there on two or more successive occasions.
प्रश्न 23 · Question 23 · Module C
फील्ड की स्थिति: आप उधारकर्ता के घर गए, पर वह घर पर नहीं है। एक पड़ोसी पूछता है कि आप क्यों आए हैं। आपको क्या करना चाहिए?
- A. पड़ोसी से कहें कि उसे बता दे, बैंक जल्दी ही मकान ज़ब्त कर लेगा
- B. पड़ोसी को बकाया बता दें ताकि लोग उस पर पैसा भरने का दबाव डालें
- C. जाने से पहले उसके दरवाज़े पर बकाया लोन की पर्ची चिपका दें
- D. कहें कि निजी काम है और लोन का ज़िक्र किए बिना लौट जाएँ
सही उत्तर: D. कहें कि निजी काम है और लोन का ज़िक्र किए बिना लौट जाएँ
व्याख्या: RBI RBC निर्देश पैरा 445 और 446: उधारकर्ता को सबके सामने शर्मिंदा करना या परिवार, रेफरी और दोस्तों की निजता में दखल देना मना है, और एजेंट को ग्राहक की जानकारी पूरी तरह गोपनीय रखनी होती है। बाद में दोबारा आएँ या सीधे उधारकर्ता से संपर्क करें।
English version
Q23. Field situation: you visit a borrower, but he is not at home. A neighbour asks why you have come. What should you do?
A. Ask the neighbour to warn him that the bank will soon seize his house · B. Tell the neighbour about the dues so that people will push him to pay · C. Stick a note about the overdue loan on his door before you leave · D. Say it is a personal matter and leave without mentioning the loan
Answer: D. Say it is a personal matter and leave without mentioning the loan. RBI RBC Directions paras 445 and 446: no acts that humiliate the borrower publicly or intrude on the privacy of family, referees and friends, and agents keep strict customer confidentiality. Come back later or contact the borrower directly.
प्रश्न 24 · Question 24 · Module C
फील्ड की स्थिति: उधारकर्ता दरवाज़ा खोलकर कहता है, "मुझे कैसे पता कि आपको सच में बैंक ने भेजा है?" आपको उसे क्या दिखाना चाहिए?
- A. बैंक का नोटिस, बैंक का अधिकार-पत्र और अपना ID कार्ड
- B. अपना विज़िटिंग कार्ड, और कहें कि एजेंसी ऑफिस में फोन कर लें
- C. फोन पर उसका लोन स्टेटमेंट, क्योंकि वह सिर्फ बैंक के पास होता है
- D. सिर्फ अपना IIBF DRA सर्टिफिकेट, क्योंकि उससे पहचान साबित होती है
सही उत्तर: A. बैंक का नोटिस, बैंक का अधिकार-पत्र और अपना ID कार्ड
व्याख्या: RBI RBC निर्देश पैरा 442(3) कहता है कि एजेंट का बैंक के नोटिस की कॉपी, बैंक का अधिकार-पत्र (authorisation letter) और बैंक या एजेंसी का दिया पहचान-पत्र साथ रखना उचित होगा। माइक्रोफाइनेंस लोन के लिए पैरा 414 कहता है कि एजेंट इन्हें साथ रखेगा।
English version
Q24. Field situation: a borrower opens the door and says, "How do I know the bank really sent you?" What should you show him?
A. The bank's notice, its authorisation letter and your ID card · B. Your visiting card, and ask him to call the agency office · C. His loan statement on your phone, since only the bank has it · D. Only your IIBF DRA certificate, since that proves who you are
Answer: A. The bank's notice, its authorisation letter and your ID card. RBI RBC Directions para 442(3) says it would be appropriate for the agent to carry a copy of the bank's notice and the bank's authorisation letter, along with the identity card issued by the bank or the agency. For microfinance loans, para 414 says the agent shall carry them.
प्रश्न 25 · Question 25 · Module C
फील्ड की स्थिति: उधारकर्ता बकाया का कुछ हिस्सा आपको नकद देता है। सही तरीका क्या है?
- A. ठीक उतनी रकम की सही रसीद दें और बैंक के तरीके से पैसा जमा करें
- B. रकम अपनी डायरी में लिख लें और अगली बार आकर रसीद दे दें
- C. पैसा ले लें और सबूत के लिए WhatsApp पर धन्यवाद का मैसेज भेज दें
- D. पूरी EMI की रसीद दे दें ताकि वह खुश रहे और आगे भी भरता रहे
सही उत्तर: A. ठीक उतनी रकम की सही रसीद दें और बैंक के तरीके से पैसा जमा करें
व्याख्या: यह हमारी व्यावहारिक सलाह है, RBI का अलग नियम नहीं: जितनी रकम मिली, ठीक उतनी की सही रसीद दें, और अपने बैंक की तय वसूली और रसीद प्रक्रिया का पालन करें। सही रसीद न मिलने पर उधारकर्ता को अपना भुगतान साबित करना मुश्किल हो सकता है।
English version
Q25. Field situation: the borrower pays part of his overdue amount to you in cash. What is the right thing to do?
A. Give a proper receipt for the exact amount and deposit it as the bank requires · B. Write the amount in your own diary and bring him a receipt on your next visit · C. Take the cash and send him a thank-you message on WhatsApp as proof of payment · D. Give a receipt for the full EMI so that he feels good and keeps on paying
Answer: A. Give a proper receipt for the exact amount and deposit it as the bank requires. This is our practical advice, not a separate RBI rule: give a proper receipt for the exact amount received, and follow your bank’s authorised collection and receipt procedure. Without a correct receipt the borrower may find it hard to prove what he paid.
प्रश्न 26 · Question 26 · Module C
फील्ड की स्थिति: उधारकर्ता शांति से कहता है, "पिछले महीने मेरी नौकरी चली गई। मैं भरना चाहता हूँ, पर अभी नहीं भर सकता।" आपको क्या करना चाहिए?
- A. कहें कि आज कुछ न भरा तो कल बैंक उसका मकान ले लेगा
- B. बात सुनें, कारण नोट करें और बैंक को बताएँ; बैंक क्रेडिट काउंसलिंग दिला सकता है
- C. जब तक वह कहीं से पैसा न ले आए, उसे हर घंटे फोन करते रहें
- D. उसके दोस्तों और साथ काम करने वालों से कहें कि बकाया EMI के लिए उसे उधार दें
सही उत्तर: B. बात सुनें, कारण नोट करें और बैंक को बताएँ; बैंक क्रेडिट काउंसलिंग दिला सकता है
व्याख्या: RBI RBC निर्देश पैरा 451: जहाँ बैंक को लगे कि किसी उधारकर्ता का मामला सहानुभूति से विचार करने लायक है, वहाँ बैंक को क्रेडिट काउंसलर की सेवाएँ लेने के लिए प्रोत्साहित किया गया है। पैरा 445 धमकी, झूठे और भ्रामक दावे, बार-बार कॉल, और परिवार, संदर्भ-दाताओं और दोस्तों की निजता में दख़ल को मना करता है।
English version
Q26. Field situation: a borrower says calmly, "I lost my job last month. I want to pay, but I cannot right now." What should you do?
A. Tell him the bank will take his house tomorrow unless he pays something today · B. Listen, note the reason and report it to the bank, which may offer credit counselling · C. Keep calling him every hour until he finds the money from somewhere · D. Ask his friends and co-workers to lend him money for the overdue EMIs
Answer: B. Listen, note the reason and report it to the bank, which may offer credit counselling. RBI RBC Directions para 451 encourages banks to use credit counsellors where the bank finds that a particular borrower's case deserves sympathetic consideration. Para 445 bars threats, false and misleading claims, persistent calling, and intruding on the privacy of family, referees and friends.
मुफ़्तविषय: Module A · Banking basics · Module D · NBFCs · Module C · Recovery conduct and skills · Module B · Loans and recovery law
IIBF DRA Mock Test · Free sample (English)
असली परीक्षा की तरह तय समय में 5 प्रश्नों के उत्तर दें। इसके बाद हर प्रश्न का सही उत्तर, उसका कारण और उस पर लगा आपका समय दिखेगा। लगभग 6 मिनट · मुफ़्त · साइन-इन की ज़रूरत नहीं।
5 प्रश्न हल करने हैं
अभी शुरू करेंलगभग 6 minयह मुफ़्त है · साइन-इन की ज़रूरत नहीं
आपके परिणाम में दिखेगा कि हर प्रश्न पर कितना समय लगा।
मॉड्यूल D: NBFC पर अतिरिक्त अध्ययन (4 प्रश्न) / Module D: Additional Reading on NBFCs
इस पेज पर मॉड्यूल D के सबसे कम (4) प्रश्न हैं: NBFC का फेयर प्रैक्टिसेज़ कोड (भाषा, जुर्माना मोटे अक्षरों में), NBFC के लिए भी कॉल का समय, और RBI लोकपाल (ओम्बड्समैन) तक पहुँचने का सही क्रम।
The fewest questions on this page (4): the NBFC Fair Practices Code (language, penalty in bold), calling hours for NBFCs too, and the right order for reaching the RBI Ombudsman.
प्रश्न 27 · Question 27 · Module D
RBI के NBFC फेयर प्रैक्टिसेज़ कोड के अनुसार NBFC को उधारकर्ता से किस भाषा में पत्र-व्यवहार करना चाहिए?
- A. उस भाषा में जो NBFC के स्टाफ के लिए सबसे आसान हो
- B. सिर्फ हिंदी में, क्योंकि वह राजभाषा है
- C. स्थानीय भाषा में, या उस भाषा में जो उधारकर्ता समझता हो
- D. सिर्फ अंग्रेज़ी में, क्योंकि लोन के कागज़ कानूनी होते हैं
सही उत्तर: C. स्थानीय भाषा में, या उस भाषा में जो उधारकर्ता समझता हो
व्याख्या: RBI (NBFC – ज़िम्मेदार व्यावसायिक आचरण) निर्देश, 2025, पैरा 10: उधारकर्ता से हर पत्र-व्यवहार स्थानीय भाषा में या उस भाषा में होना चाहिए जो उधारकर्ता समझता हो।
English version
Q27. Under RBI's Fair Practices Code for NBFCs, in what language should an NBFC write to its borrower?
A. Any language the NBFC's staff find easiest to use · B. Hindi only, because it is the official language · C. The vernacular, or a language the borrower understands · D. English only, because loan papers are legal documents
Answer: C. The vernacular, or a language the borrower understands. RBI (Non-Banking Financial Companies – Responsible Business Conduct) Directions, 2025, para 10: all communications to the borrower are in the vernacular language or a language understood by the borrower.
प्रश्न 28 · Question 28 · Module D
NBFC को लोन एग्रीमेंट में देर से भुगतान का जुर्माना (penalty) किस तरह दिखाना होता है?
- A. नीचे फुटनोट में
- B. सिर्फ अपनी वेबसाइट पर
- C. बाद में अलग पत्र में
- D. मोटे (bold) अक्षरों में
सही उत्तर: D. मोटे (bold) अक्षरों में
व्याख्या: RBI (NBFC – ज़िम्मेदार व्यावसायिक आचरण) निर्देश, 2025, पैरा 13: ज़्यादा ब्याज और जुर्माने की शिकायतें आम हैं, इसलिए NBFC लोन एग्रीमेंट में देर से भुगतान का जुर्माना मोटे (bold) अक्षरों में लिखता है।
English version
Q28. How must an NBFC show the penalty for late repayment in its loan agreement?
A. In a footnote · B. On its website only · C. In a separate letter later · D. In bold type
Answer: D. In bold type. RBI (Non-Banking Financial Companies – Responsible Business Conduct) Directions, 2025, para 13: because many complaints are about high interest and penal charges, the NBFC mentions the penalties for late repayment in bold in the loan agreement.
प्रश्न 29 · Question 29 · Module D
फील्ड की स्थिति: आप एक NBFC के लिए दोपहिया वाहन लोन (माइक्रोफाइनेंस नहीं) का बकाया वसूलते हैं। आप उधारकर्ता को सुबह 7:30 बजे फोन करना चाहते हैं ताकि वह काम पर जाने से पहले मिल जाए। क्या यह ठीक है?
- A. नहीं, NBFC एजेंट सिर्फ सुबह 9 से शाम 6 बजे के बीच कॉल कर सकते हैं
- B. हाँ, समय की पाबंदी सिर्फ बैंकों पर है, NBFC पर नहीं
- C. नहीं, NBFC के लिए भी सुबह 8 बजे से पहले वसूली कॉल मना है
- D. हाँ, अगर कॉल छोटी और विनम्र हो तो कोई भी समय ठीक है
सही उत्तर: C. नहीं, NBFC के लिए भी सुबह 8 बजे से पहले वसूली कॉल मना है
व्याख्या: RBI (NBFC – ज़िम्मेदार व्यावसायिक आचरण) निर्देश, 2025, पैरा 100 में बैंकों जैसी ही पाबंदी है: सुबह 8:00 बजे से पहले या शाम 7:00 बजे के बाद वसूली कॉल नहीं। सुबह 9 से शाम 6 की सीमा माइक्रोफाइनेंस लोन के लिए है।
English version
Q29. Field situation: you collect an overdue two-wheeler loan for an NBFC (not a microfinance loan). You plan to phone the borrower at 7:30 a.m. so you catch him before work. Is that allowed?
A. No, NBFC agents may call only between 9 a.m. and 6 p.m. · B. Yes, the time limits apply only to banks, not to NBFCs · C. No, recovery calls before 8 a.m. are barred for NBFCs too · D. Yes, if the call is short and polite, any time is fine
Answer: C. No, recovery calls before 8 a.m. are barred for NBFCs too. RBI (Non-Banking Financial Companies – Responsible Business Conduct) Directions, 2025, para 100 applies the same bar as banks: no recovery calls before 8:00 a.m. or after 7:00 p.m. The 9 a.m. to 6 p.m. limit is for microfinance loans.
प्रश्न 30 · Question 30 · Module D
उधारकर्ता RBI ओम्बड्समैन (लोकपाल) योजना के तहत NBFC के रिकवरी एजेंट की शिकायत करना चाहता है। उसे सबसे पहले क्या करना होगा?
- A. समझौते के लिए लोक अदालत जाना होगा
- B. ऋण वसूली अधिकरण (DRT) में केस करना होगा
- C. मुंबई में IIBF को शिकायत भेजनी होगी
- D. पहले खुद NBFC से शिकायत करनी होगी
सही उत्तर: D. पहले खुद NBFC से शिकायत करनी होगी
व्याख्या: RBI एकीकृत लोकपाल योजना में शिकायत तभी ली जाती है जब ग्राहक ने पहले रेगुलेटेड एंटिटी (यहाँ NBFC) से लिखित रूप में या किसी और तरीके से, सबूत के साथ, शिकायत की हो और समय पर जवाब न मिला हो या वह संतुष्ट न हो। इसके बाद लोकपाल को शिकायत cms.rbi.org.in पर ऑनलाइन, ई-मेल से या कागज़ पर भेजी जा सकती है (क्लॉज़ 11)।
English version
Q30. A borrower wants to complain about an NBFC's recovery agent under the RBI Ombudsman scheme. What must he do first?
A. Go to a Lok Adalat for a settlement · B. File a case in the Debts Recovery Tribunal · C. Send the complaint to IIBF in Mumbai · D. Complain to the NBFC itself first
Answer: D. Complain to the NBFC itself first. Under the RBI Integrated Ombudsman Scheme a complaint is admitted only if the customer first complained to the regulated entity (here the NBFC), in writing or another mode with proof, and got no reply in time or was not satisfied. The complaint to the Ombudsman may then be filed online at cms.rbi.org.in, by e-mail or on paper (clause 11).
उत्तर कुंजी / Answer key
सभी 30 प्रश्नों के सही विकल्प एक जगह। Every answer in one place.
| प्रश्न / Q | मॉड्यूल / Module | सही विकल्प / Answer | उत्तर (हिंदी) |
|---|---|---|---|
| 1 | A | C | ड्राइविंग लाइसेंस |
| 2 | A | D | लेन-देन की तारीख से कम से कम 5 साल |
| 3 | A | D | एक तय (specified) बैंक पर |
| 4 | A | B | 30 दिन |
| 5 | A | B | 2 साल तक जेल, या चेक की रकम के दोगुने तक जुर्माना, या दोनों |
| 6 | A | D | लेनदार और देनदार: बैंक लेनदार (creditor) है |
| 7 | A | D | हर बैंक में एक जमाकर्ता के 5 लाख रुपये तक |
| 8 | B | A | 90 दिन से ज़्यादा |
| 9 | B | A | जब ब्याज और मूलधन का पूरा बकाया चुका दिया जाए |
| 10 | B | B | हाइपोथिकेशन (दृष्टिबंधक) |
| 11 | B | C | 60 दिन |
| 12 | B | C | 45 दिन |
| 13 | B | C | 20 लाख रुपये |
| 14 | B | A | यह सिविल कोर्ट की डिक्री माना जाता है और इसकी अपील नहीं होती |
| 15 | B | B | खेती की ज़मीन |
| 16 | C | B | सुबह 8 बजे से पहले और शाम 7 बजे के बाद |
| 17 | C | A | बैंक उधारकर्ता को बताता है; नया एजेंट नोटिस, अधिकार-पत्र और ID साथ रखता है |
| 18 | C | A | शिकायत का निपटारा होने तक केस रिकवरी एजेंट को नहीं भेजता |
| 19 | C | B | कॉल रिकॉर्ड होती है, और ग्राहक को यह बताने जैसी सावधानी रखी जाती है |
| 20 | C | C | बैंक की, क्योंकि वह प्रधान (principal) है |
| 21 | C | B | कुछ समय के लिए किसी इलाके में बैंक के रिकवरी एजेंट रखने पर रोक |
| 22 | C | A | जब वह लगातार 2 या ज़्यादा बार उस तय जगह पर न आए |
| 23 | C | D | कहें कि निजी काम है और लोन का ज़िक्र किए बिना लौट जाएँ |
| 24 | C | A | बैंक का नोटिस, बैंक का अधिकार-पत्र और अपना ID कार्ड |
| 25 | C | A | ठीक उतनी रकम की सही रसीद दें और बैंक के तरीके से पैसा जमा करें |
| 26 | C | B | बात सुनें, कारण नोट करें और बैंक को बताएँ; बैंक क्रेडिट काउंसलिंग दिला सकता है |
| 27 | D | C | स्थानीय भाषा में, या उस भाषा में जो उधारकर्ता समझता हो |
| 28 | D | D | मोटे (bold) अक्षरों में |
| 29 | D | C | नहीं, NBFC के लिए भी सुबह 8 बजे से पहले वसूली कॉल मना है |
| 30 | D | D | पहले खुद NBFC से शिकायत करनी होगी |
मुख्य संख्याएँ / Key numbers
ये संख्याएँ 30 जून 2026 तक जारी नियमों के अनुसार हैं। These figures follow the rules issued up to 30 June 2026.
| नियम / Rule | संख्या / Figure | स्रोत / Source |
|---|---|---|
| वसूली कॉल का समय (बैंक और NBFC, माइक्रोफाइनेंस नहीं) / Recovery calling hours | सुबह 8 बजे से पहले और शाम 7 बजे के बाद नहीं / not before 8 a.m. or after 7 p.m. | RBI बैंक निर्देश पैरा 445; NBFC निर्देश पैरा 100 |
| माइक्रोफाइनेंस: कठोर व्यवहार / Microfinance harsh practice | सुबह 9 बजे से पहले या शाम 6 बजे के बाद कॉल / calls before 9 a.m. or after 6 p.m. | RBI बैंक निर्देश पैरा 408-416 |
| NPA (टर्म लोन, कृषि लोन नहीं) / NPA for a term loan (not a farm loan) | ब्याज या किस्त 90 दिन से ज़्यादा बकाया / interest or instalment overdue more than 90 days | RBI IRACP निर्देश, 2025 |
| SARFAESI धारा 13(2) नोटिस / s.13(2) notice | 60 दिन में भुगतान / 60 days to pay | SARFAESI Act, 2002 |
| SARFAESI धारा 17: DRT में आवेदन / s.17 application to the DRT | कार्रवाई की तारीख से 45 दिन / 45 days from the measure taken | SARFAESI Act, 2002 |
| DRT में केस / DRT case | बैंक का वसूली आवेदन: ₹20 लाख या ज़्यादा का कर्ज़ / bank recovery application: debt of ₹20 lakh or more | RDB Act, 1993; S.O. 4312(E), 2018 |
| चेक बाउंस: माँग का नोटिस / cheque bounce: demand notice | चेक लौटने की जानकारी मिलने के 30 दिन में नोटिस; नोटिस मिलने के 15 दिन में भुगतान / notice within 30 days of learning of the dishonour; payment within 15 days of receipt of the notice | NI Act धारा 138 |
| चेक बाउंस: सज़ा / cheque bounce: punishment | 2 साल तक, या चेक की रकम के दोगुने तक जुर्माना, या दोनों / up to 2 years, fine up to twice the amount, or both | NI Act धारा 138 |
| लेन-देन का रिकॉर्ड / transaction records | कम से कम 5 साल / at least 5 years | RBI KYC निर्देश पैरा 50 |
| जमा बीमा / deposit insurance | हर बीमित बैंक में हर जमाकर्ता के ₹5 लाख तक (मूलधन + ब्याज) / up to ₹5 lakh per depositor per insured bank, principal and interest | DICGC |
| RBI लोकपाल / RBI Ombudsman | पहले योजना में शामिल बैंक/NBFC को लिखित या किसी और माध्यम से शिकायत, सबूत रखें; 30 दिन (या लागू लंबी अवधि) में जवाब न मिले या जवाब से संतुष्ट न हों, तो उस अवधि के ख़त्म होने या बैंक/NBFC से मिले सबसे हाल के पत्र, ई-मेल या संदेश की तारीख, जो बाद में हो, से 90 दिन के अंदर लोकपाल: ऑनलाइन (cms.rbi.org.in), ई-मेल या डाक से / complain to the covered bank or NBFC first and keep proof; no reply in 30 days (or a longer applicable period) or an unsatisfactory reply; then the Ombudsman within 90 days of that period ending or the entity’s last communication, whichever is later, online, by e-mail or on paper | RB-IOS 2026, खंड 10 और 11 |
| DRA परीक्षा / DRA exam | 100 प्रश्न, 2 घंटे, 50 पर पास, 9 महीने में 3 प्रयास / 100 questions, 2 hours, pass 50, 3 attempts in 9 months | IIBF Rules & Syllabus 2024 |
आगे का अभ्यास / More practice
30 प्रश्नों के बाद घड़ी लगाकर अभ्यास करें। ProSyllabus DRA मॉक टेस्ट में 20-20 प्रश्नों के 3 प्रैक्टिस मॉक हैं, हर मॉक 24 मिनट का: यानी असली परीक्षा की रफ़्तार, 1.2 मिनट प्रति प्रश्न। ये असली प्रश्नपत्र से छोटे हैं (IIBF की परीक्षा 100 प्रश्न, 2 घंटे, पास 50)। हर मॉक में चारों मॉड्यूल हैं, हिंदी या अंग्रेज़ी में, और 5 प्रश्नों का नमूना बिना साइन इन के मुफ़्त है। ये हमारे अपने प्रश्न हैं, IIBF के नहीं, और इस पेज के 30 प्रश्नों से अलग हैं; कोई भी अभ्यास पास होने की गारंटी नहीं देता।
In English: for timed practice there are 3 ProSyllabus practice mocks of 20 questions, 24 minutes each (the real exam’s pace of 1.2 minutes a question; the real paper is 100 questions in 2 hours, pass 50), in Hindi or English, with a free 5-question sample and no sign-in needed. They are our own questions, not IIBF’s, and not the 30 on this page.
मुफ़्तविषय: Module A · Banking basics · Module D · NBFCs · Module C · Recovery conduct and skills · Module B · Loans and recovery law
IIBF DRA Mock Test · Free sample (English)
असली परीक्षा की तरह तय समय में 5 प्रश्नों के उत्तर दें। इसके बाद हर प्रश्न का सही उत्तर, उसका कारण और उस पर लगा आपका समय दिखेगा। लगभग 6 मिनट · मुफ़्त · साइन-इन की ज़रूरत नहीं।
5 प्रश्न हल करने हैं
अभी शुरू करेंलगभग 6 minयह मुफ़्त है · साइन-इन की ज़रूरत नहीं
आपके परिणाम में दिखेगा कि हर प्रश्न पर कितना समय लगा।
अक्सर पूछे जाने वाले सवाल
क्या ये प्रश्न IIBF के प्रश्नपत्र से लिए गए हैं?
नहीं। ये हमारे अपने अभ्यास प्रश्न हैं, जो इसी पेज के लिए RBI नियमों, कानूनों और IIBF सिलेबस से लिखे गए हैं। IIBF अपने प्रश्न किसी से साझा नहीं करता। (No: these are our own practice questions, not IIBF questions.)
क्या DRA परीक्षा हिंदी में दे सकते हैं?
हाँ। परीक्षा हिंदी, अंग्रेज़ी और 9 अन्य भाषाओं में होती है। ध्यान रखें कि आपकी ट्रेनिंग एजेंसी फॉर्म में भाषा "हिंदी" लिखे; भाषा न लिखी हो तो IIBF अंग्रेज़ी मानता है।
DRA परीक्षा में कितने प्रश्न होते हैं और पास होने के लिए कितने अंक चाहिए?
100 प्रश्न, 100 अंक, 2 घंटे। पास होने के लिए 100 में से 50 अंक चाहिए। गलत उत्तर पर अंक नहीं कटते, इसलिए हर प्रश्न का उत्तर दें।
DRA परीक्षा में कितने प्रयास मिलते हैं?
प्रशिक्षण पूरा होने की तारीख से 9 महीने के अंदर 3 प्रयास। इसमें पास न हों तो फिर से DRA प्रशिक्षण लेना होगा, उसके बाद ही नई परीक्षा दे सकते हैं।
बैंक के लोन के लिए रिकवरी कॉल किस समय कर सकते हैं?
RBI के नियमों के अनुसार बकाया लोन की वसूली के लिए सुबह 8 बजे से पहले और शाम 7 बजे के बाद कॉल नहीं कर सकते (बैंक पैरा 445, NBFC पैरा 100)। ये दोनों पैरा माइक्रोफाइनेंस लोन पर लागू नहीं होते। माइक्रोफाइनेंस वसूली में बार-बार कॉल करना या सुबह 9 बजे से पहले या शाम 6 बजे के बाद कॉल करना कठोर व्यवहार में गिना जाता है (बैंक पैरा 410, NBFC पैरा 91)।
सबसे ज़्यादा प्रश्न किस मॉड्यूल से आते हैं?
IIBF मॉड्यूल-वार बँटवारा प्रकाशित नहीं करता। इस पेज पर हमने मॉड्यूल C से सबसे ज़्यादा (11) प्रश्न रखे हैं, क्योंकि वही एजेंट का रोज़ का काम है। यह हमारा बँटवारा है, IIBF का नहीं।
DRA की तैयारी किस किताब से करें?
IIBF की अपनी पाठ्य-पुस्तक "Hand Book on Debt Recovery" (2024 संस्करण, Taxmann) IIBF की DRA वेबसाइट पर हिंदी समेत 11 भाषाओं में सूचीबद्ध है। IIBF यह भी कहता है कि नियम बदलते रहते हैं, इसलिए RBI के ताज़ा निर्देश भी पढ़ें।
दिसंबर 2026 की परीक्षा में किन नियमों से प्रश्न आ सकते हैं?
IIBF के नियम के अनुसार सितंबर से फरवरी की परीक्षाओं में 30 जून तक जारी नियमों पर विचार किया जाता है, इसलिए 12 दिसंबर 2026 की परीक्षा के लिए 30 जून 2026 तक जारी नियम मान्य हैं। IIBF यह नहीं बताता कि इनमें से कौन-से नियम पूछे जाएँगे। इस पेज के उत्तर उन्हीं नियमों पर आधारित हैं।
More in this series
Sources
- official — IIBF: Certificate Examination for Debt Recovery Agents, Rules & Syllabus 2024 (PDF)
- official — IIBF: Certificate Examination for Debt Recovery Agents (exam schedule, fee, medium, study material)
- official — RBI: Reserve Bank of India (Commercial Banks – Responsible Business Conduct) Directions, 2025 (28.11.2025, updated 01.10.2026): paras 326-347 Fair Practices Code, 408-416 microfinance, 442-454 recovery agents
- official — RBI: Reserve Bank of India (Non-Banking Financial Companies – Responsible Business Conduct) Directions, 2025 (PDF)
- official — RBI: Reserve Bank of India (Commercial Banks – Know Your Customer) Directions, 2025
- official — RBI: Reserve Bank of India (Commercial Banks – Income Recognition, Asset Classification and Provisioning) Directions, 2025
- official — India Code (Ministry of Law and Justice): Negotiable Instruments Act, 1881; SARFAESI Act, 2002; Recovery of Debts and Bankruptcy Act, 1993; Legal Services Authorities Act, 1987
- official — DICGC: deposit insurance (Rs 5 lakh per depositor per bank)
- official — RBI: Reserve Bank – Integrated Ombudsman Scheme, 2026, in force 01.07.2026 (PDF)
official = a document published by the conducting body. reported = a news or coaching site we could not check against an original. Where sources disagree this page says so rather than picking one.